PPF maturity date falls on a holiday or you don’t withdraw immediately: what happens to your money?
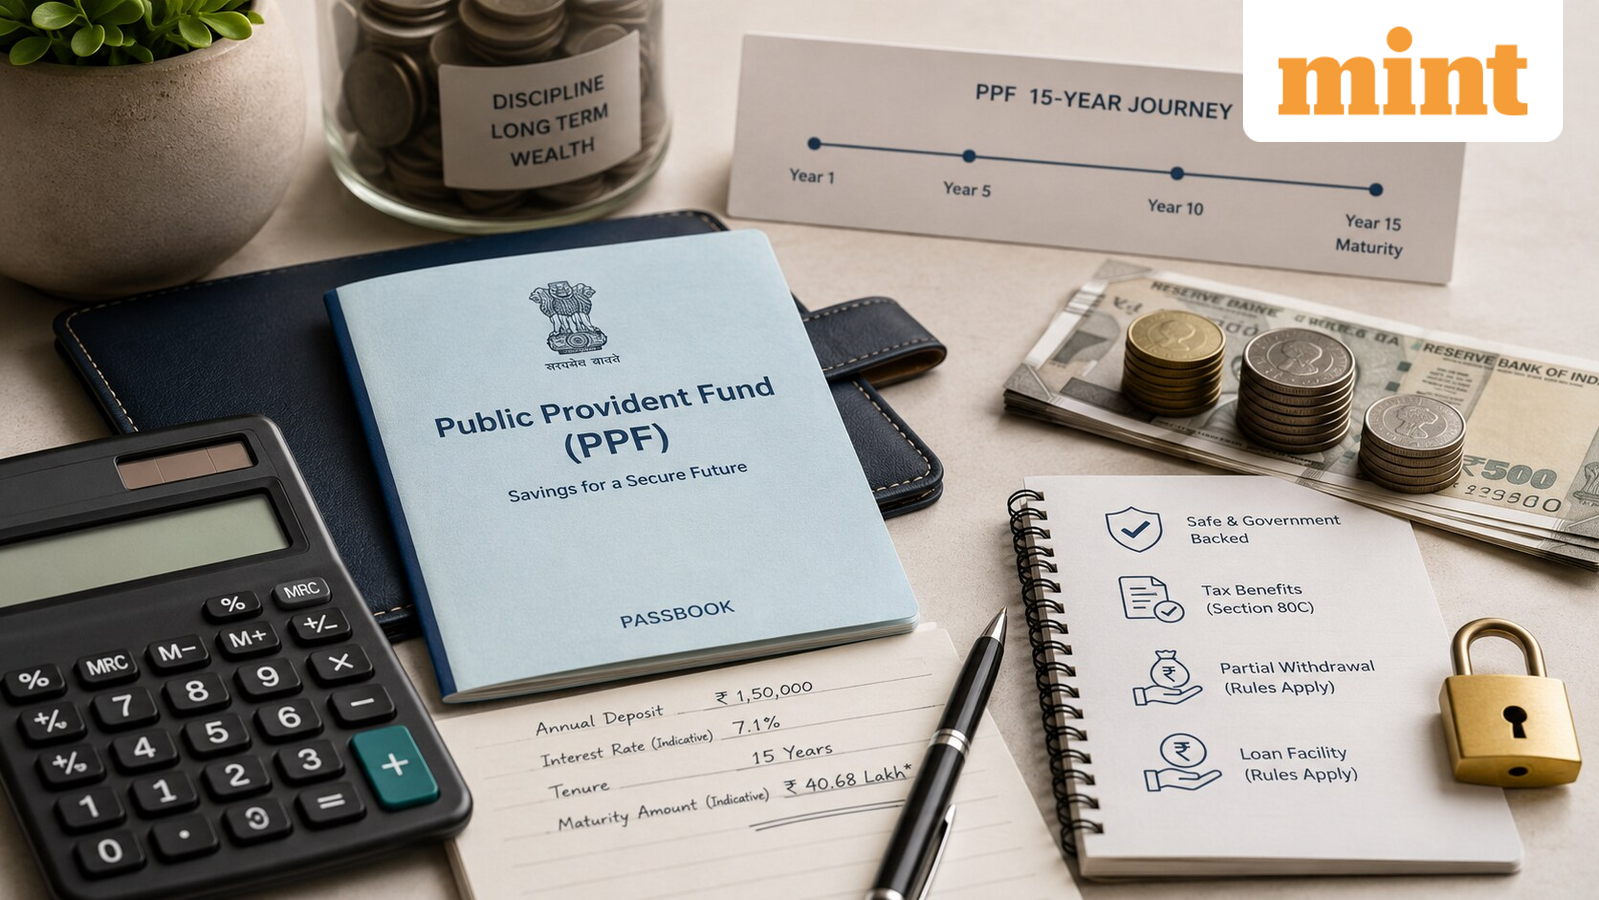
A Public Provident Fund (PPF) account comes with a 15-year maturity period, after which investors can withdraw the principle amount plus interest. The maturity is calculated from the end of the financial year in which the account was opened, rather than from the exact date of the first deposit.
For example, if you opened a PPF account in November 2011 (FY 2011-12), the account will mature on April 1, 2027. This is because the 15-year maturity period was counted from March 31, 2012 in this case.
However, the maturity date may fall on a weekend and depositors can also delay withdrawing the money because they forgot about the account or were unaware of the deadline. What happens in such cases? Let’s find out.
Does PPF lock in for another 5 years if not withdrawn?
No, after the 15-year maturity period, there are no penalties or restrictions on withdrawals but only until a certain time period.
A PPF account holder must submit Form 4 (or Form H at some institutions) to their bank or post office within one year of maturity to extend the tenure of their account and keep making contributions. This is mandatory and failing to do so can affect liquidity, withdrawal flexibility, and future deposits.
An investor has the option to extend the tenure of their PPF account in blocks of five years, as many times as they want.
What if you don’t take any action?
If you don’t submit Form 4 within one year of the PPF account’s maturity, the account still continues in blocks of five years by default. However, fresh contributions are not allowed in such cases.
The existing balance continues to earn interest at the applicable rate (currently it is 7.1% per annum), and you can withdraw money only once per financial year.
Form 4 can be downloaded from your bank’s website, such as the State Bank of India (SBI), HDFC, or Bank of Baroda. You can also get it by physically visiting the branch or post office where you have the PPF account.
Post-maturity options
PPF, which is government-backed long-term savings scheme, enjoys one of the most favourable tax treatments among investment options in India, as it falls under the EEE (Exempt-Exempt-Exempt) category. This means eligible contributions, interest and the maturity amount are all exempt from tax.
Once the 15-year period ends, an investor can choose what to do next from these three main options:
- Extension without deposits: The account continues to earn interest on the existing balance. You are allowed one withdrawal per financial year.
- Extension with deposits: Extend the account in blocks of 5 years by submitting Form 4 within one year of maturity.
The decision to close or extend your PPF account should depend on an individual’s immediate financial needs. If you have an urgent requirement for the money, then a withdrawal can be made. However, if you don’t need the capital right away, extending the account is advisable as it gives long-term returns.