SGB premature redemption October 2026: 4 tranches eligible for early exit, check RBI dates and deadlines
Sovereign Gold Bond investors holding some of the older 2019-20 and 2020-21 series have a chance to exit their investments before maturity in October. The Reserve Bank of India has scheduled premature redemption for four SGB tranches this month, giving eligible investors an opportunity to encash their bonds after completing the mandatory five-year holding period.
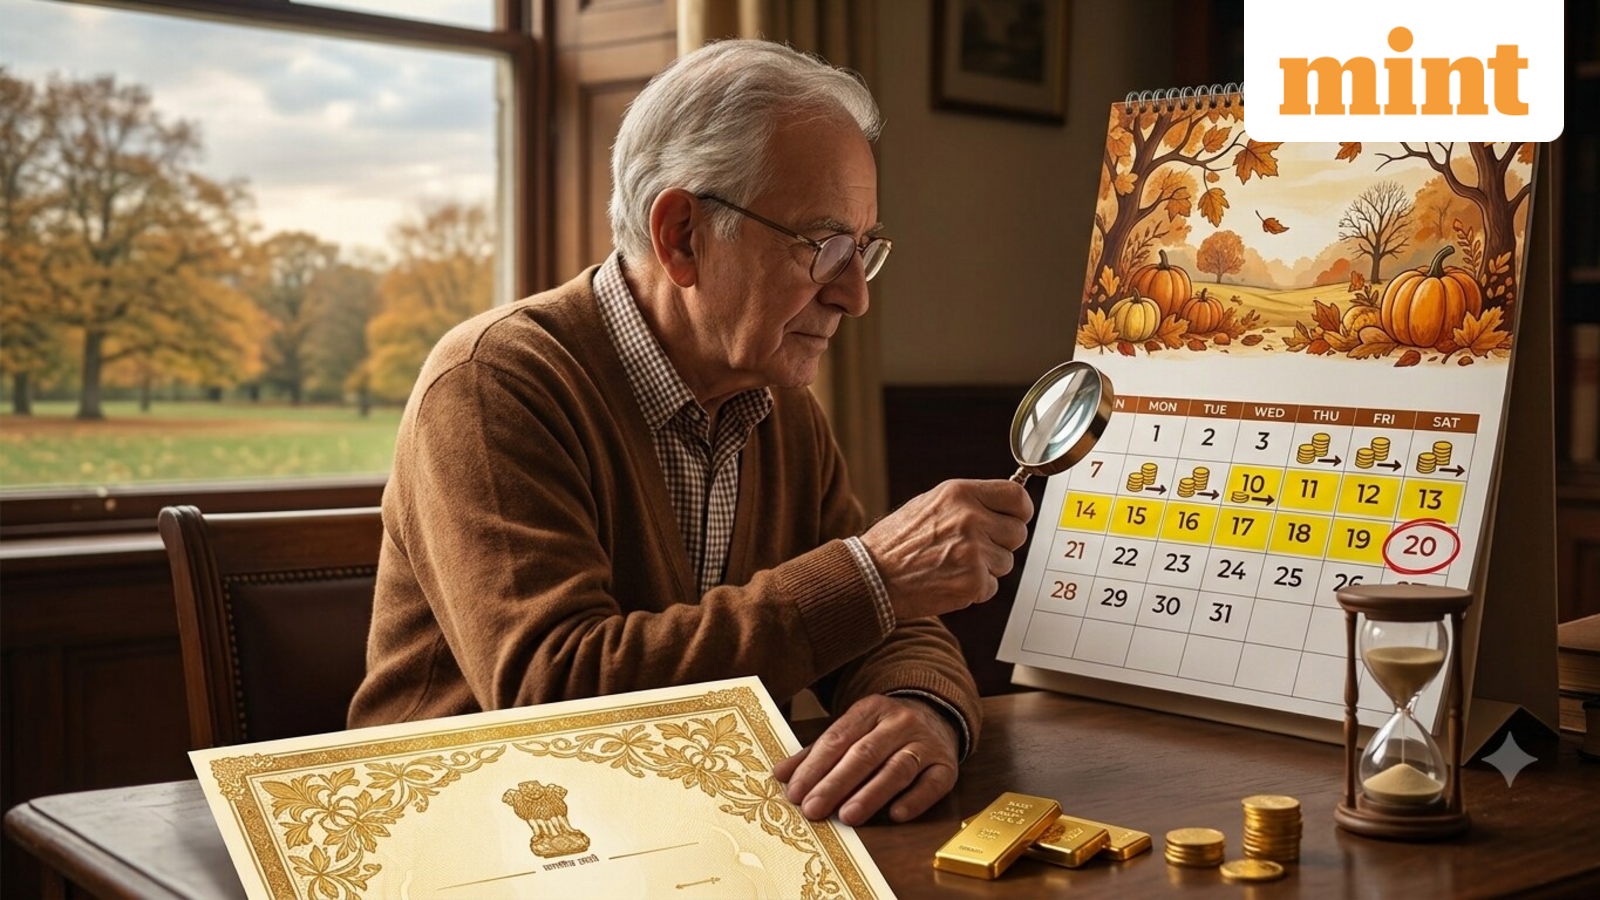
But investors cannot simply wait until the redemption date to act. The request for premature redemption has to be submitted within a specified window that opens weeks before the actual payment date. Missing that deadline means waiting for the next eligible redemption opportunity.
Here are the four SGB series eligible for premature redemption in October, the last dates by which investors need to submit their requests and what they should check before exiting.
Four SGB tranches are eligible for premature redemption in October
According to the RBI schedule, the four October redemptions are:
|
SGB tranche |
Issue date |
Premature redemption date |
Request window |
| 2019-20 Series V | 15 October 2019 | 15 October 2026 | 14 September–5 October 2026 |
| 2020-21 Series VII | 20 October 2020 | 19 October 2026 | 19 September–9 October 2026 |
| 2020-21 Series I | 28 April 2020 | 28 October 2026 | 26 September–19 October 2026 |
| 2019-20 Series VI | 30 October 2019 | 30 October 2026 | 29 September–21 October 2026 |
| Source: RBI | |||
The first deadline is particularly important for investors holding SGB 2019-20 Series V. They have until 5 October 2026 to submit their request for the 15 October redemption. The other three deadlines fall on 9 October, 19 October and 21 October, respectively.
Investors should check the exact series and issue date of the SGB in their demat account or holding statement before making a request.
SGBs can be redeemed after five years, but not on any day
SGBs have an eight-year tenor, but the scheme permits premature redemption after five years from the date of issue, subject to the applicable redemption schedule. The RBI releases a calendar specifying when individual tranches can be redeemed before maturity.
The premature redemption facility is different from selling an SGB on the stock exchange. An exchange sale is a market transaction in which the investor exits at the prevailing traded price. Premature redemption, on the other hand, takes place through the RBI’s scheduled mechanism.
For eligible investors choosing the RBI route, the redemption value is linked to the prevailing gold price rather than the original issue price. Under the SGB framework, the redemption price is based on the simple average of the closing price of 999-purity gold for the previous three working days, published by the India Bullion and Jewellers Association.
Tax exemption now depends on holding the SGB until maturity
There is another important change for investors considering premature redemption this year.
From 1 April 2026, the capital-gains exemption for SGB redemption was narrowed. The amended provision provides the exemption where an individual holds the SGB continuously from the date of original issue until maturity. The change applies to the tax year 2026-27 and subsequent tax years.
This creates an important distinction for investors using the five-year premature-redemption facility. The exemption specifically refers to redemption on maturity, whereas an investor using the RBI’s premature-redemption window is exiting before the bond’s scheduled maturity.
Therefore, investors should not assume that a gain arising from premature redemption automatically gets the same capital-gains exemption available for an SGB held until maturity.
The tax treatment should also not be confused with the interest earned on SGBs. The bonds carry a fixed interest component, which is separate from the capital gain or loss arising from the gold-linked redemption value.