Stocks Push Higher as Fed Rate Hike Chances Fall
The S&P 500 Index ($SPX) (SPY) is up by +0.63% today, the Dow Jones Industrial Average ($DOWI) (DIA) is up by +0.15%, and the Nasdaq 100 Index ($IUXX) (QQQ) is up +0.75%. December E-mini S&P futures (ESZ26) are up +0.55%, and December E-mini Nasdaq futures (NQZ26) are up +0.72%.
Stock indexes are moving higher today as inflation concerns eased after the Q2 core PCE price index was revised lower and the Aug core PCE price index rose less than expected. The better-than-expected inflation news reduced the chance of a Fed rate hike next month to 35% from 52% on Tuesday. Also, signs of growth in the US economy supported stocks after Q2 GDP was revised higher, the Sep ADP employment change rose more than expected, and Aug personal spending rose the most in 5 months. Stocks added to their gains after the Sep MNI Chicago PMI expanded at the strongest pace in 4 months.
Join 200K+ Subscribers:
Find out why the midday Barchart Brief newsletter is a must-read for thousands daily.
Stocks are awaiting Micron Technology’s earnings after the close today to gauge demand for AI spending.
US MBA mortgage applications fell -6.0% in the week ended September 25, with the purchase mortgage sub-index down -4.3% and the refinancing mortgage sub-index down -8.7%. The average 30-year fixed-rate mortgage rose +18 bp to a 2.75-year high of 7.30% from 7.12% the prior week.
The US Sep ADP employment change rose by +90,000, stronger than expectations of +75,000.
US Aug personal spending rose by +0.9% m/m, right on expectations and the largest increase in five months. Aug personal income rose +0.2% m/m, weaker than expectations of +0.5% m/m.
The US Aug core PCE price index, the Fed’s preferred inflation gauge, rose +0.2% m/m and +3.0% y/y, weaker than expectations of +0.3% m/m and +3.3% y/y.
US Q2 GDP was revised upward to +2.2% (q/q annualized), stronger than expectations of no change at +1.5%, as Q2 personal consumption was revised upward to +3.8% from the previously reported +3.4%. The Q2 core PCE price index was revised downward to +3.3% from the previously reported +3.6%.
The US Sep MNI Chicago PMI rose +11.7 to 58.8, stronger than expectations of 51.0 and the fastest pace of expansion in four months.
Positive economic news from China supported global growth prospects and boosted stocks. The China Sep manufacturing PMI rose +0.3 to 50.1, right on expectations. The China Sep non-manufacturing PMI rose +1.2 to 50.2, stronger than expectations of 49.2.
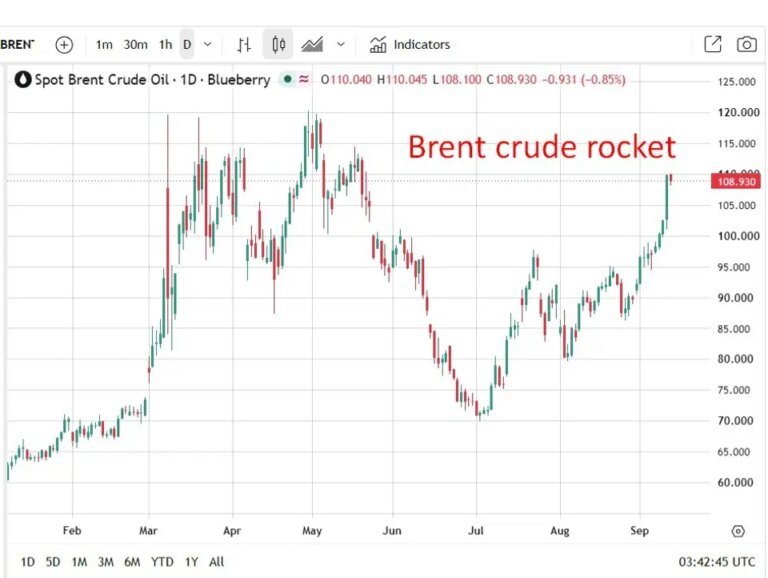
Nov WTI crude oil prices (CLX26) are up more than +2% today after Russia announced that it was extending a ban on most diesel exports through October, further tightening theglobal market Russia began its diesel export ban in July after Ukrainian drone and missile attacks damaged Russian refineries. Gains in crude are limited after JPMorgan Chase said Middle East crude exports have rebounded to 17.5 million bpd, or about 98% of pre-war levels, although flows of gasoline, diesel and distillates were at 3 million bpd, or 58% of pre-war levels.
Markets are discounting a 35% chance of a +25 bp Fed rate hike at the next FOMC meeting on October 27-28.
Overseas stock markets are mixed today. The Euro Stoxx 50 is down -0.36%. China’s Shanghai Composite closed up +0.318%. Japan’s Nikkei-225 Stock Average closed up +1.94%.
Interest Rates
December 10-year T-notes (ZNZ6) are down -3 ticks today. The 10-year T-note yield is up +1.3 bp to 5.268%. Dec T-notes gave up an early advance today and turned lower on stronger-than-expected US economic news, including Q2 GDP, the Sep ADP employment change, and the Sep MNI Chicago PMI. Also, today’s +2% increase in WTI crude oil is raising inflation expectations and is bearish for T-notes. The 10-year breakeven inflation rate rose to a 2-week high of 2.365% today.
T-notes initially moved higher today as inflation concerns eased after the Q2 core PCE price index was revised lower and the Aug core PCE price index rose less than expected. The weaker-than-expected inflation readings reduced the chance of a Fed rate hike next month to 35% from 52%. T-notes also have support from some month- and quarter-end buying by bond fund managers today as they extend duration in their portfolios.
European government bond yields are mixed today. The 10-year German bund yield is down -4.9 bp to 3.577%. The 10-year UK gilt yield is up +0.5 bp to 5.415%.
The German Sep unemployment change rose +12,000, showing a weaker labor market than expectations of 500.
German Aug retail sales rose +1.3% m/m, the largest increase in 14 months but slightly weaker than expectations of +1.5% m/m.
German Sep CPI (EU harmonized) rose +0.6% m/m and +3.3% y/y, stronger than expectations of +0.5% m/m and +3.2% y/y, with the +3.3% y/y gain the largest year-on-year increase in 2.75 years.
UK Q2 GDP was revised upward to +0.5% q/q and +1.4% y/y from the previously reported +0.4% q/q and +1.2% y/y.
Markets are discounting a 28% chance of a +25 bp ECB rate hike at the ECB’s next meeting on October 29.
US Stock Movers
Software stocks are stronger today, supporting gains in the broader market. Atlassian Corp (TEAM) is up more than +3%, and Salesforce (CRM) is up more than +3% to lead gainers in the Dow Jones Industrials. Also, Datadog (DDOG), Adobe Systems (ADBE), Autodesk (ADSK), and Intuit (INTU) are up more than +2%. In addition, Microsoft (MSFT), Palantir Technologies (PLTR), ServiceNow (NOW), and Cadence Design Systems (CDNS) are up more than +1%.
Cybersecurity stocks are strengthening today, providing support to the overall market. Gen Digital (GEN) is up more than +6%, and Okta (OKTA) and Palo Alto Networks (PANW) are up more than +3%. Also, Fortinet (FTNT) and SentinelOne (S) are up more than +2%, and Crowdstrike Holdings (CRWD) and Zscaler (ZS) are up more than +1%.
Hewlett Packard Enterprise (HPE) is up more than +7% to lead gainers in the S&P 500 after raising its fiscal 2027 networking segment revenue growth outlook.
Huntington Ingalls Industries (HII) is up more than +2% after the US Navy awarded the company a $5.1 billion contract for the accomplishment of the USS Harry S. Truman refueling and complex overhaul.
Target (TGT) is up more than +1% after HSBC upgraded the stock to buy from hold with a price target of $190.
Moderna (MRNA) is down more than -7% to lead losers in the S&P 500 after Citigroup downgraded the stock to sell from neutral with a price target of $80.
Cal-Maine Foods (CALM) is down more than -3% after reporting Q1 net sales of $539.6 million, below the consensus of $552.2 million.
Northrup Grumman (NOC) is down more than -3% after losing out to Boeing on the $20 billion contract to build the Navy’s next-generation fighter jet.
Earnings Reports (9/30/2026)
Cal-Maine Foods Inc (CALM), Conagra Brands Inc (CAG), FactSet Research Systems Inc (FDS), Jabil Inc (JBL), Micron Technology Inc (MU), Progress Software Corp (PRGS).
On the date of publication,
did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes.
For more information please view the Barchart Disclosure Policy
here.