How QSBS Stacking and Packing Cuts Capital Gains Tax
You have spent years building the company. A potential purchaser is on the horizon, and your first instinct is to mitigate the government’s take. Here is what too many founders learn too late: with the proper equity structure, held correctly, the answer can be a nominal amount or even nothing at all. Section 1202 of the Internal Revenue Code has allowed this since 1993, and the One Big Beautiful Bill Act of July 2025 made it considerably more generous.
The gap between founders who plan for this and founders who do not is measured in millions, and it comes down to two techniques—practitioners call them “stacking” and “packing”—which must be in place before a buyer is at the table.
What the Break Actually Does
Corporate stock that meets the definition of qualified small business stock—Referred to as “QSBS”—can be sold free of federal capital gains tax, up to a ceiling. That ceiling is the greater of two numbers: $15 million (indexed for inflation beginning in 2027), or 10 times what you paid for the stock. For stock issued on or before July 4, 2025, the fixed amount is $10 million.
Below illustrates the detail that makes everything else possible: the ceiling belongs to each shareholder, and it starts fresh for each company. Own qualifying stock in three companies, and you have three ceilings. Give shares away and—done properly—the recipient arrives with a ceiling of their own.
Does the Company and Stock Qualify?
Not every small business can issue QSBS. There are 5 primary hurdles.
-
It must be a C corporation. This is where many promising situations fall apart: LLCs, partnerships and S corporations simply cannot issue QSBS stock.
-
It’s capped at a value when the shares are initially issued. Gross assets—measured mostly by tax basis rather than market value—must be $75 million or less immediately before and after issuance (and $50 million for stock issued on or before July 4, 2025).
-
It must be in the right kind of business. At least 80% of assets must be working in a “qualified trade or business.” Congress carved out a long list of exceptions: most professional services—health, law, accounting, consulting, architecture, engineering, performing arts, athletics, financial services and brokerage—plus banking, insurance, leasing and investing, farming, mining, and hotels and restaurants. A catch-all also excludes any business whose principal asset is the reputation or skill of its people. Software and manufacturing tend to fit comfortably, while professional practices generally do not.
-
The stock must be “Originally Issued.” For the shareholder’s stock to qualify for the QSBS exemption, it must have been issued directly by the corporation. What this means is that if you purchase stock from another shareholder, the stock will not be considered “originally issued” and therefore does not qualify as QSBS. Gifts of stock received either from someone during their life or upon death, although technically not received from the corporation, nevertheless may still qualify as QSBS, assuming the other requirements are met.
-
Five-Year Requirement. The stock must have been held by the taxpayer for five years in order to qualify for the 100% exemption (meaning $10 million under the old rules; $15 million post-July 2025). Under the OBBB, the holding period may be as little as three years to receive a 50% exemption (meaning $5 million under the old rules; $7.5 million post-July 2025), or four years to receive a 75% exemption (meaning $7.5 million under the old rules; $11.25 million post-July 2025). For the recipient of a gift of stock, the holding period is calculated based on the original shareholder. For example, if the original shareholder held the stock for three years, then gifted it to his or her child, who held it for two years, and then sold it, they would meet the five-year holding requirement and receive the 100% exemption. As these rules are technical and may change from time to time, it is important to engage a tax professional to ensure you have the most up-to-date information.
Started as something else? You are not necessarily out of the game. Companies that now look like ideal QSBS candidates often began life as something else. There are routes that may still be taken—generally a conversion paired with the issuance of new stock—thus, converting a flow-through business into C corporation form, whether it is taxed today as a partnership, a disregarded entity or an S corporation. What a conversion cannot do, however, is reach backward: the holding period and the exclusion run from the new shares forward, not from the day one founded the business.
Stacking: Turning One Ceiling into Several
Here is where planning starts to pay. Because the ceiling follows the shareholder rather than the company, the useful question becomes how many shareholders you are willing to gift and the nature of the gift. Generally, gifts should be limited to family members (or the “natural objects of one’s bounty,” in legal terms). Gifts to unrelated parties run the risk of being seen as a sham.
As mentioned earlier, when you gift QSBS shares away, the recipient steps into your shoes — treated as having acquired the stock the way you did and credited with the years you held it. The clock does not restart. And if the recipient is a separate taxpayer, they bring a separate ceiling.
The phrase “separate taxpayer” is key. Often, irrevocable trusts used in typical estate planning are taxable as grantor trusts — transparent for income tax purposes, with everything they earn landing on the grantor’s own return. Consequently, a grantor trust is of no use here. What is essential is a non-grantor trust: treated as its own taxpayer, having its own tax ID number, filing its own tax return. Only then does it bring its own exclusion.
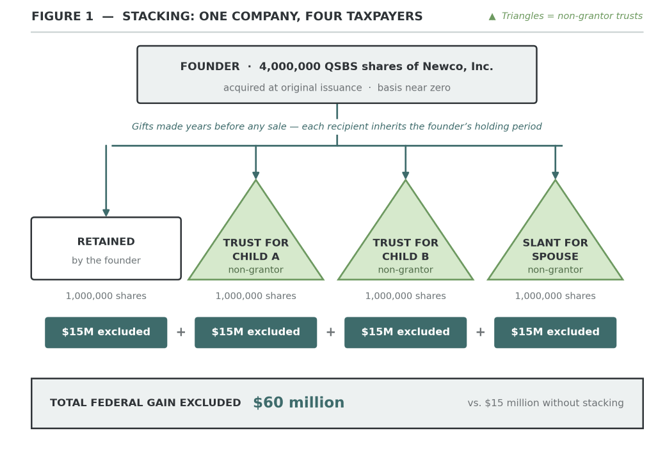
Picture a founder with two children. She creates a non-grantor trust for each, gifts a block of shares to each, and adds a spousal lifetime access non-grantor trust — a “SLANT” — so her husband remains a primary beneficiary and keeps a block herself. Four taxpayers, four ceilings. Figure 1 shows how the arithmetic lands.
Nonetheless, four things must be respected:
-
Timing is close. Gifting after a binding letter of intent is received, or the week before signing, and you invite the IRS to take the position that you had already earned the income and simply handed off the check. Months of daylight are comfortable; weeks are often not. Early gifts are also more efficient—shares are valued when given, so less of the lifetime exemption is consumed.
-
Do not create “mirrored trusts”. Where several trusts share the same grantor and beneficiaries and exist mainly to save tax, the IRS can treat them as one. Vary the beneficiaries, terms, trustees and funding dates.
-
The gifts must be irrevocable gifts. Irrevocable means what it says. The shares, and eventually the proceeds, belong to the trust and its beneficiaries rather than to you.
-
Caveats and planning pointers: Some tax professionals employ “incomplete” gift trusts where the estate tax exemption has already been utilized. This may be considered risky as there would likely be no estate planning or “business purpose” for such a gift or gifts other than for QSBS planning. Accordingly, caution is warranted here. In some cases, to avoid this issue, the shares, while at a low value, should be given as soon as possible to a trust having multiple beneficiaries. Then, when the shares grow substantially, the trust assets are out of the estate, and if structured properly, can provide for multiple “stacks” based on the number of people involved. The trust could also be structured to give the grantor a fair amount of control after the shares are disposed.
Packing: Lifting the Ceiling Itself
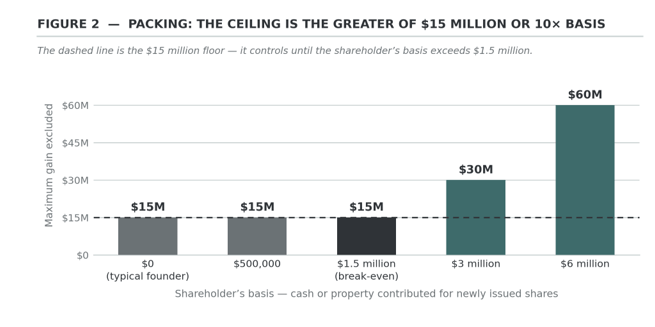
Remember that the ceiling was the greater of two numbers—and so far, we have discussed only one. Very few consider the 10-times-basis alternative. This is because most founders paid next to nothing for their shares, and ten times nothing is still nothing. Packing changes that are deliberate, building a basis until the multiple becomes a larger number. The crossover is $1.5 million: below it, the $15 million floor governs, above it, the multiple climbs fast. Figure 2 shows its shape.
You build a basis by transferring cash or property into the corporation in exchange for newly issued shares. Property is the efficient route, because Section 1202 measures contributed property at what it is worth rather than at what you paid for it: contribute an asset worth $6 million, and you have created $6 million of basis and a $60 million ceiling. This is why packing comes up most often when an LLC or partnership incorporates—the business is valued on conversion, and that value becomes the basis.
Three things are required:
-
The contribution must buy new shares. Adding capital to shares you already own does nothing for your ceiling —perhaps a frustrating technicality, but a firm one.
-
The company still must pass the $75 million gross asset test immediately after the contribution. Pack too enthusiastically, and you disqualify the very shares you were trying to protect.
-
Your holding period for the newly received stock starts over at the time of contribution, and appreciation that accrued before then stays taxable. Packing raises the ceiling on future gain; it does not reach back, and shelter gain you have already built up
The Part Worth Remembering
None of this is particularly exotic. The primary challenge is the sequence of events and technical rules, namely that planning must take place early, while the company is relatively small, the shares are low-value, and no transaction is in sight. Often, by the time a term sheet circulates, most of these doors have quietly closed. Having the conversation as early as possible, when the company is showing serious potential, but not too near to an exit, is the sweet spot for doing this planning.
In any event, it is essential that a tax professional be consulted early in the process.