Want SIFs in your portfolio? Should you invest directly or choose the new mutual fund-PRIM route — experts explain
With the introduction of SEBI’s new Portfolio Managers Route for Investing in Mutual Fund units (PRIM), investors can get a PMS-like way to invest in direct mutual fund units and SIFs.
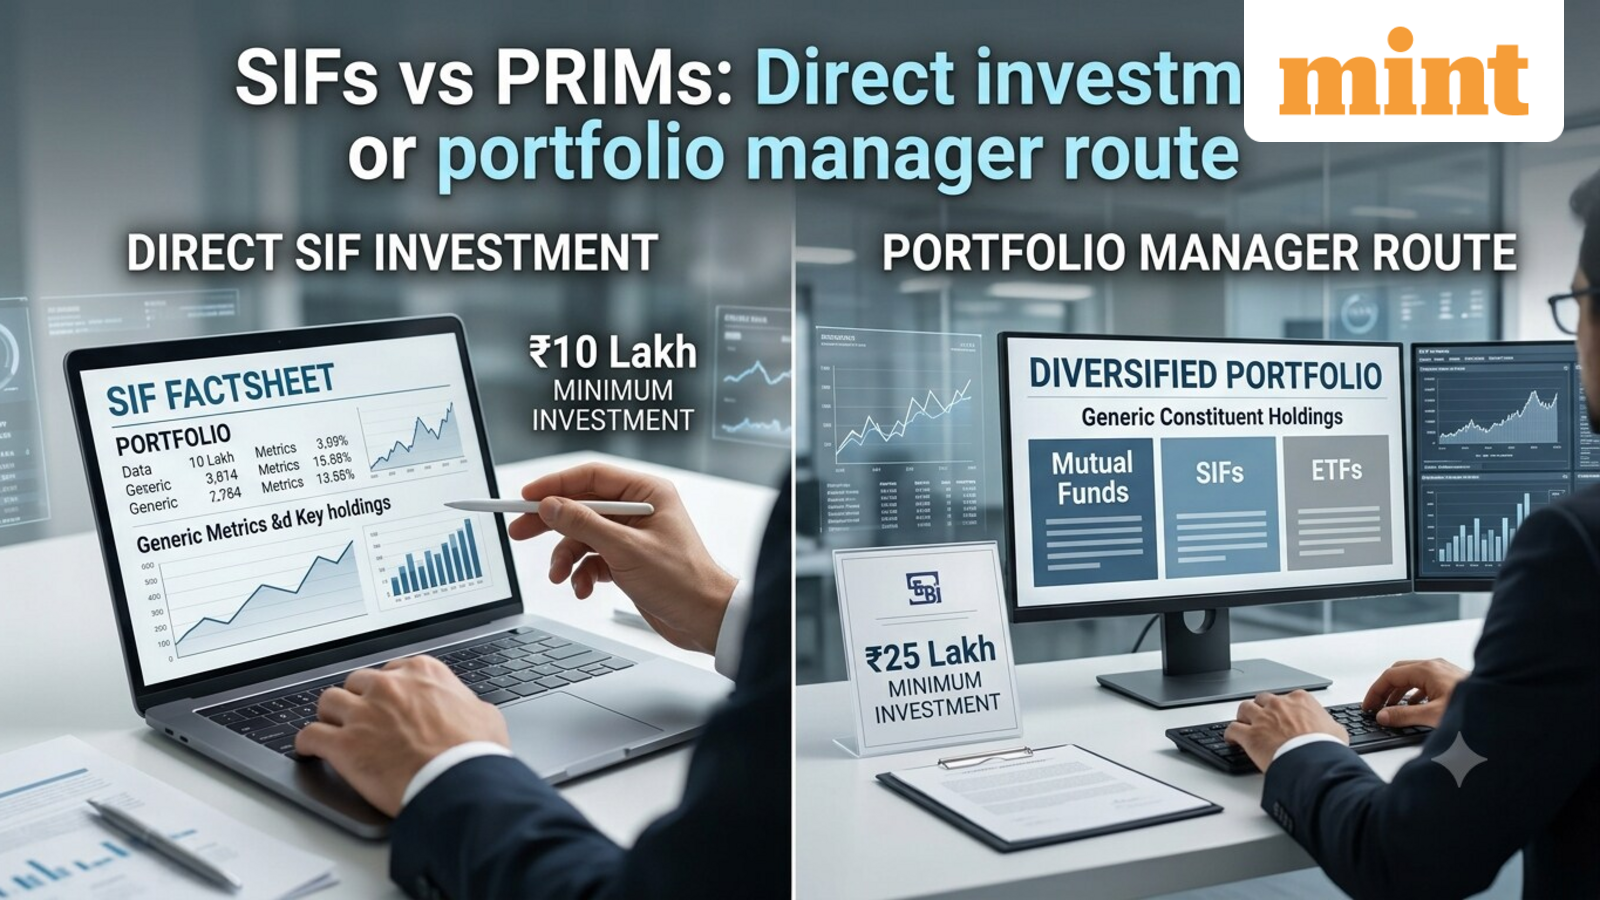
Through this route, investors can get a professionally managed portfolio of mutual funds, SIFs and ETFs, with a minimum investment of ₹25 lakh.
SIFs are specialised investment funds that follow specific strategies, with a minimum investment of ₹10 lakh. This raises the question: should investors invest in SIFs directly or use the PRIM route? Here’s what experts have to say.
Which route is better for SIF investment?
“Start with what each route is. An SIF is a product. PRIM is a portfolio management service. An investor who buys an SIF directly is choosing one strategy. An investor who goes through a portfolio manager under PRIM is paying someone to decide which strategies to hold, how much of each, and when to change the mix,” Sandeep Jethwani, Co-founder, Dezerv, said.
The real question, then, is whether you need that second layer of decision-making and whether you are willing to pay for it. Under PRIM, the portfolio manager invests in direct mutual fund plans too, but the investor pays a management fee of up to 1% of assets, Jethwani added.
For some investors, choosing an SIF directly may be a natural extension of how they already manage their investments. For others, paying for professional portfolio management may bring greater convenience and discipline. The right choice depends on the investor’s needs, risk appetite and level of involvement, Sanjiv Bajaj, Joint Chairman and MD at Bajaj Capital, added.
PRIM is a holistic portfolio, while an SIF is a standalone offering. Having an experienced portfolio manager select, size and integrate SIF strategies, based on the investor’s portfolio and risk profile, ensures that the exposure is structurally professionally monitored and actively rebalanced, Shobhit Mathur, Co-Founder at Ionic Wealth, mentioned.
What is the difference between investing directly in a SIF or through PRIM?
The simplest way to look at the difference is that with a direct SIF investment, the investor is choosing the strategy, while through PRIM, the investor is giving the portfolio manager a broader mandate to construct and manage the portfolio, Bajaj mentioned.
A direct SIF investor tracks NAVs, reads monthly portfolio disclosures and has to evaluate the strategy. Under PRIM, the investor receives consolidated reporting on the portfolio as a whole against a benchmark, and the manager handles scheme-level tracking, Jethwani added.
Can an investor instruct a portfolio manager to invest only in SIFs and exclude mutual fund units in PRIM?
Under PRIM, the portfolio manager has the ability to construct portfolios using eligible direct mutual fund investments, including SIFs. So, an investor can certainly have a conversation with the portfolio manager about their preferred investment universe and the kind of exposure they are looking for, Bajaj mentioned.
But it should not be assumed that every PRIM portfolio can automatically be structured that way, Bajaj said.
Nothing reported so far requires a minimum allocation to conventional mutual fund units. The final regulations and circulars are still to be notified, and investors should wait for that text before considering any structure final, Jethwani added.
Who is better suited to the direct SIF route?
The direct route suits investors who have ₹10 lakh or more they are comfortable committing to a single strategy, understand how long-short and derivative-based strategies behave in falling and sideways markets, and have the time to read strategy documents and review holdings. They value control and lower cost over delegation, Jethwani said.
PRIM may be more relevant for someone who has a larger investible corpus of more than ₹25 lakh and would rather have a professional take a more holistic view of the portfolio. The value there is not simply in accessing an SIF, but in having someone think about asset allocation, diversification and rebalancing across the portfolio, Bajaj added.
Disclaimer: This story is for educational purposes only. The views and recommendations made above are those of individual analysts or broking companies, and not of Mint. We advise investors to check with certified experts before making any investment decisions.
About the Author
Sheetal Goel is a Content Producer at Livemint, where she covers corporate developments, personal finance, business trends, markets, and SEBI-related updates. She focuses on simplifying complex financial concepts and presenting them in a clear, reader-friendly manner, thereby helping audiences better understand investment trends, personal finance, and market developments. Her writing focuses on making finance more accessible to everyday readers while maintaining clarity, accuracy, and relevance.
She holds a degree in Economics (Hons.) along with an MBA in Finance, which has helped her develop a strong foundation in financial analysis, market understanding, and business reporting. Before joining journalism, she worked with finance and broking firms, where she closely followed market developments, investment strategies, and evolving industry trends. This practical exposure strengthened her understanding of financial markets. She has also written content across multiple formats and platforms, including YouTube, LinkedIn, and Instagram.
Over time, she has developed expertise in covering market-linked stories, investor-focused topics, and regulatory updates in a simplified yet informative style. She also enjoys reading and listening to Hindi poetry, reflecting her appreciation for literature and creative expression beyond the world of markets and numbers.