Inherited jewellery: How to prove its origins and avoid tax scrutiny | Personal Finance
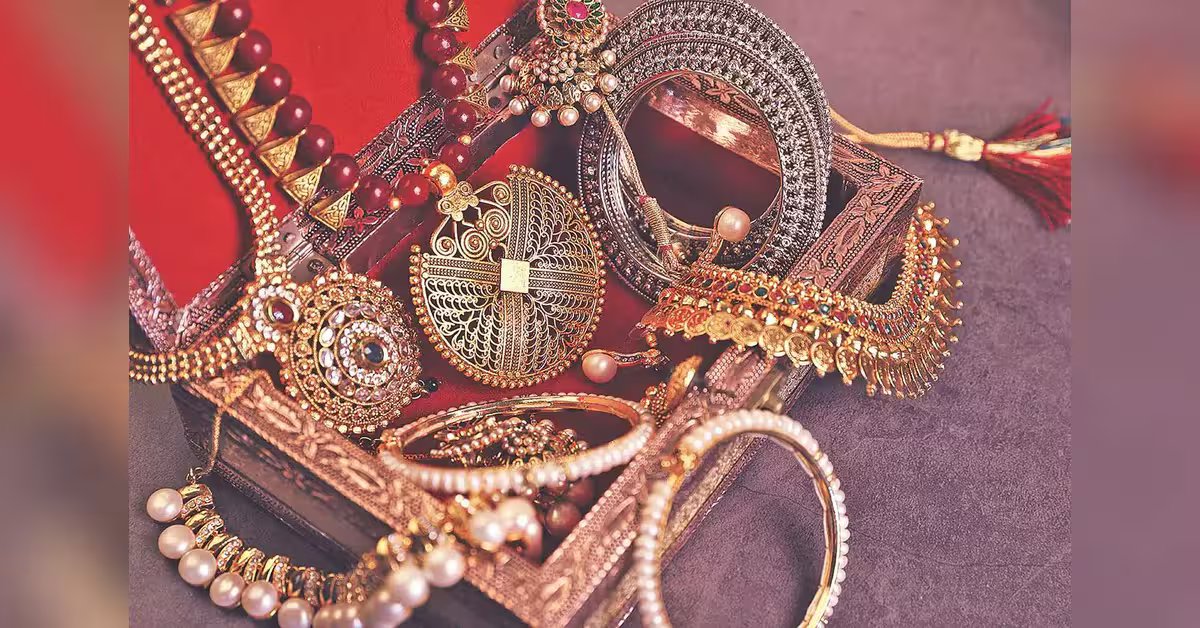
A tax search of Miraj Digvijay Shah’s premises and family lockers brought 3,233.11 grams of jewellery worth ₹1.56 crore under scrutiny. Shah said the jewellery belonged to deceased relatives and his father’s Hindu undivided family (HUF). In Miraj Digvijay Shah v. Deputy Commissioner of Income Tax (DCIT), the Kolkata Income Tax Appellate Tribunal (ITAT) accepted his explanation and ruled in his favour. The case shows why families should retain records that explain inherited jewellery long after purchase bills have disappeared.
What the assessee must prove
The assessee must explain the nature and source of jewellery and support the explanation with evidence, tax experts say. Its presence in a home or locker alone does not establish ownership.
“The tax authorities would also consider who held and accessed the locker, whether other family members used it and any earlier records of ownership. If the explanation is rejected, the jewellery may be treated as unexplained, attracting a significantly higher tax burden,” says Vishwas Panjiar, managing partner, SVAS Business Advisors.
How to establish inheritance
Records created before a search can show that jewellery belonged to a parent or grandparent and how it entered the family. Old valuation reports, wealth-tax and insurance records, wills, succession or family settlement documents, photographs and locker records can help when purchase invoices are unavailable. “No single document is necessarily conclusive; the family must present consistent evidence showing the jewellery was inherited or belonged to an earlier generation,” says Panjiar. The assessee still needs a credible explanation of the source, supported by the evidence as a whole.
Current records: Useful for the future
An inventory, photographs and a valuer’s report can identify jewellery and establish its current weight and value. A current valuation, however, cannot by itself establish when someone acquired it or who originally owned it. These records should supplement historical evidence.
“Ultimately, the assessee must establish both the ownership and source of the jewellery. If the explanation is not satisfactorily supported by evidence, the jewellery could be treated as unexplained income, potentially leading to a substantial tax liability under the applicable provisions,” says Panjiar.
Search thresholds
The Central Board of Direct Taxes (CBDT) has set search thresholds of 500 grams for a married woman, 250 grams for an unmarried woman and 100 grams for a male member. These figures do not limit how much jewellery a person may own.
“Under CBDT Instruction No. 1916 of May 11, 1994, these quantities are generally treated as explained and need not be seized during a search. Jewellery above these limits is not automatically unexplained or taxable; the officer can also exclude more based on family status, customs and circumstances,” says Neeraj Agarwala, senior partner, Nangia & Co LLP.
Families can also explain jewellery bought with disclosed or exempt income, household savings or inherited wealth through purchase bills, inheritance documents and other ownership records.
Who owns the family locker?
Separate lockers can clarify which family member owns the jewellery. Where relatives share a locker, they should keep a signed, updated inventory alongside purchase bills and inheritance or gift records.
“Under Section 524 of the Income-tax Act, 2025, jewellery found in a person’s possession or control during a search is presumed to belong to that person. Thus, the locker holder may face a presumption of ownership and would need to explain the jewellery’s ownership and source,” says Agarwala.
Document inherited jewellery
Families should record inherited jewellery with photographs, weights, descriptions, valuation reports and available purchase or legal documents. “Locker and custody records should also be preserved. The Kolkata ITAT case shows that such historical records can help establish ancestral ownership and reduce the risk of tax disputes,” says Akhil Chandna, partner and global people solutions leader, Grant Thornton Bharat.
What to do after tax addition
If the tax department makes an addition, taxpayers can challenge it before the Commissioner (Appeals) and then the ITAT. Documents showing when and how the family acquired or inherited the jewellery can strengthen an appeal.
“While appeals have prescribed filing timelines, disposal can take years, with seized assets remaining under tax authorities’ control and interest or penalty exposure continuing. So, families should maintain valuation reports, inheritance records, locker details, wills and other ownership documents to reduce the risk of prolonged disputes,” says Chandna.
The writer is a Delhi-based independent journalist