File ITR now or wait until the new 21 October tax audit deadline? What taxpayers need to know
The tax audit deadline for AY 2026-27 has been extended from 30 September to 21 October 2026. But if you have already completed your tax audit, do you need to wait until 21 October to file your ITR?
An expert explains when you can file early, what you should check first, and what happens if a mistake is found later.
Isha Sekhri, Founder, Isha Sekhri & Associates LLP, said 21 October is only the extended specified date for furnishing the tax audit report, while 21 November 2026 is the extended due date for filing the ITR.
Neither date blocks earlier filing once both are genuinely complete. The law builds in a one-month gap between them: the specified date for the audit report is defined as one month before the ITR due date, so when the audit date moved to 21 October, the ITR date moved in tandem from 31 October to 21 November to preserve that gap, she mentioned.
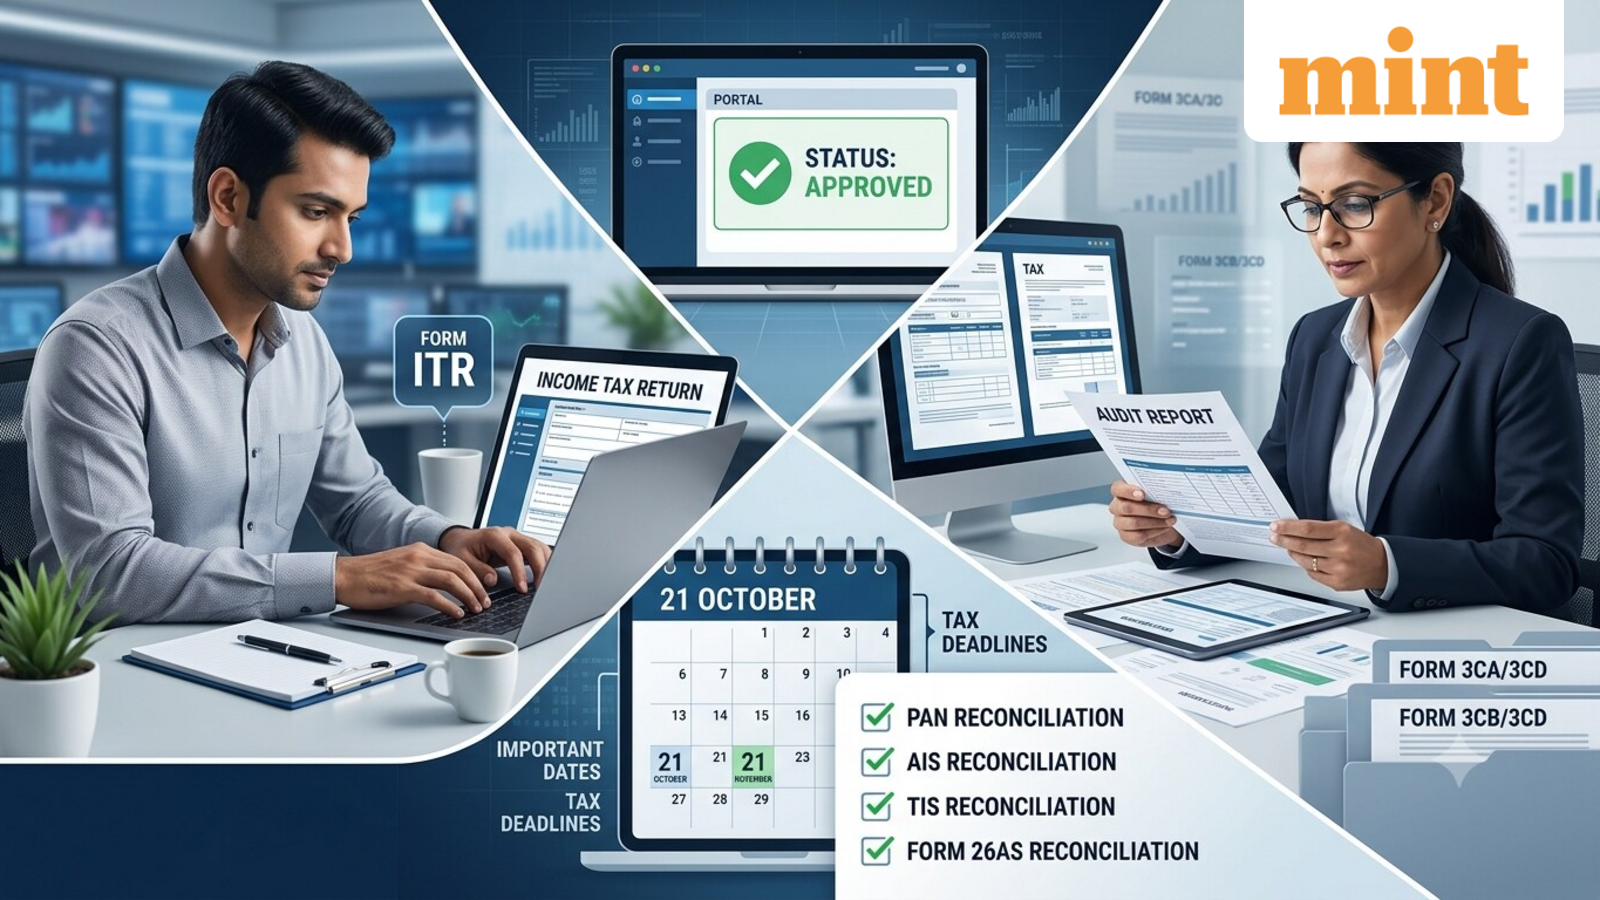
Once Form 3CA-3CD or 3CB-3CD is uploaded, the UDIN is validated, and the assessee approves the report on the portal, the ITR can be filed immediately. There is no requirement to wait until the extended deadline, she added.
What is the best practice if the tax audit is already complete?
Sekhri said there is no legal requirement to wait, as the extension is relief, not a mandate to delay. Best practice is to file as soon as the audit is genuinely finalised.
Before filing, taxpayers should confirm that the audit report shows “Approved” status with a valid acknowledgement number and UDIN. They should also ensure that the return figures match the audited financial statements and that Form 26AS, AIS and TIS data have been reconciled, as these records can continue to be updated and mismatches may trigger notices, she said.
What should taxpayers check in tax audit report before filing ITR?
Sekhri said taxpayers should check the following points:
What if a mistake is found in tax audit report after filing ITR?
The ITR can be revised if a mistake is subsequently found in the audit report. Sekhri said the ITR due date is 21 November 2026, while the revised return can be filed until 31 December 2026.
Taxpayers should not file a fresh original ITR again. Instead, the revised-return route under section 139(5) should be used.
The practical sequence is to have the chartered accountant correct and re-file the tax audit report first, followed by a revised ITR reflecting the corrected figures and referencing the revised audit report, she said.
Disclaimer: This is only for informational and educational purposes. Please consult a qualified expert for the latest laws and regulations.