Alt lenders say the sector’s growth is only set to continue
Self-employed borrowers, investors managing multiple properties, entrepreneurs with complex income structures, and Canadians navigating divorce, Canada Revenue Agency debt, or bankruptcy proceedings are increasingly landing in the alternative channel. That’s not because of a damaged credit history, but rather because of how banks define qualifying income.
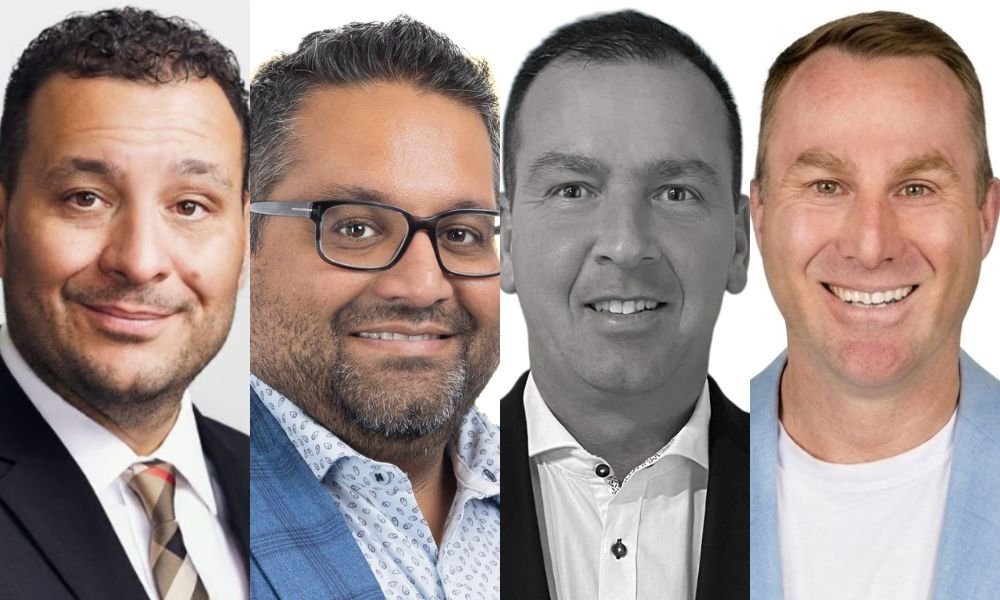
Grant Armstrong (pictured top left), chief growth officer at WealthONE Bank of Canada, said that the average FICO score of his institution’s alt borrowers sits at 763. He said that figure, in some cases, outperforms credit quality at the Big Six banks, something he said reflects a structural change in how income is assessed.
“Banks have very, very specific ways of looking at income,” he said. “That’s where the alternative lenders can come in and have a different risk appetite – to look at cashflow of the business, bank statement approach, investment properties, holdcos.”
‘No longer a short-term solution’
Joel Cote (pictured, top right), chief operating officer at Haventree Bank, agreed that the traditional profile of the alt borrower now represents a much smaller share of the channel. “It’s no longer, for many, a short-term solution,” he said. “For many clients that fit this profile, the alt solution is the prime solution.”
Prakash Bector (pictured, middle left), vice president of sales and distribution at EQ Bank, stressed that for self-employed clients, income assessment requires understanding the entire business: revenue, overhead, expenses, and how the client structures their operations.