Salary earned abroad, credited to NRE account: Does that make it taxable in India? ITAT ruling explained
For Indians working overseas, where salary is credited can sometimes create confusion about where that income is taxable. A recent Bengaluru Income Tax Appellate Tribunal (ITAT) ruling has clarified that merely receiving foreign salary in an Indian NRE bank account cannot, by itself, be a reason to treat the salary as income accruing in India.
The ruling came in Santhoshkumar Vithal Akka vs Income Tax Officer, Ward International Taxation 1(1), Bengaluru, ITA No. 2056/Bang/2025, for assessment year 2016-17, with the order pronounced on 23 September 2026.
Tax department questioned salary credited to NRE account
The taxpayer was a non-resident during the relevant assessment year and was working on a project in South Korea. His salary was fixed in US dollars and credited to his NRE account maintained with Axis Bank.
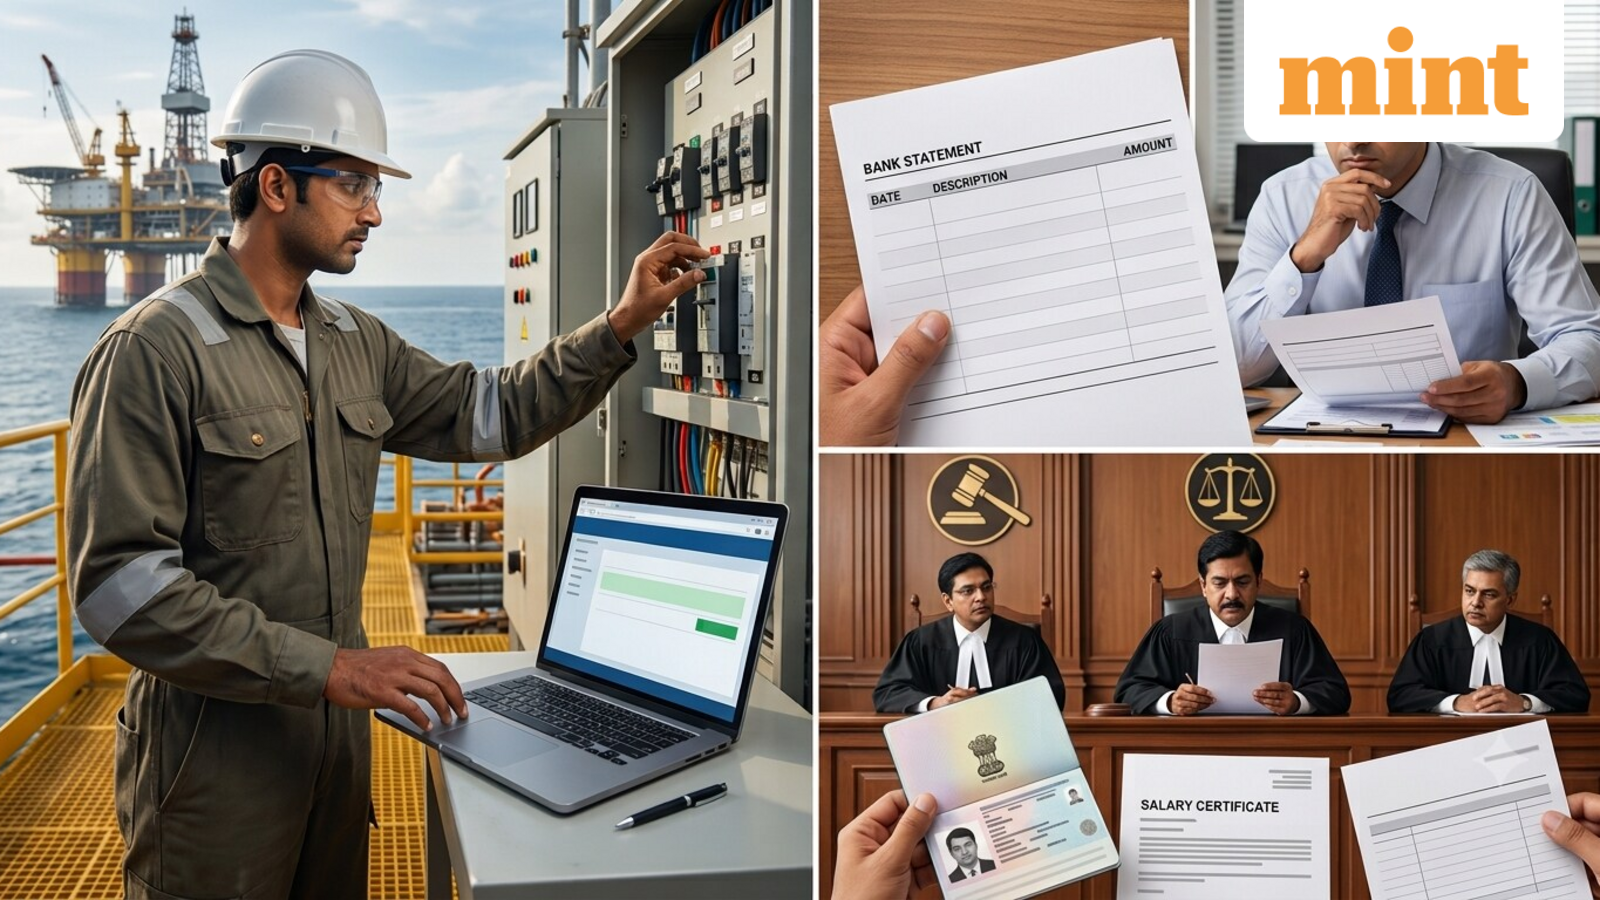
The taxpayer had originally filed his return as a non-resident. The case was subsequently reopened, and the Assessing Officer (AO) sought various details. The taxpayer eventually submitted documents including his bank statements, income computation, passport and payslips.
The AO observed that the taxpayer had received salary in US dollars in his NRE account and concluded that the salary income had not been declared in his return.
The department also noted that the taxpayer had not furnished copies of his foreign tax returns, a tax residency certificate (TRC) or proof of taxes paid abroad. The AO consequently added the salary income to his taxable income.
The taxpayer challenged the addition before the Dispute Resolution Panel (DRP), but the DRP also rejected his objections. Among other things, the DRP took the view that because the salary had been paid by the employer into a bank account in India, it was deemed to accrue or arise in India.
ITAT examined where the taxpayer actually worked
Before the ITAT, the taxpayer argued that he was a non-resident and had earned the salary while working outside India. Therefore, the fact that the salary was subsequently credited to his Indian NRE account should not make the foreign employment income taxable in India.
The Tribunal examined the employment documents and found that the taxpayer was employed by Ocean Rig UDW Inc., a company based in Athens, Greece. The company had a project connected with Samsung Heavy Industries in South Korea, and the taxpayer was identified as the supervisor who would work as an electrician at the Korean project site.
The employment assignment ran from September 2014 to 30 June 2016. His remuneration was fixed in US dollars and the bank statement showed the corresponding salary credits.
The Tribunal also examined his passport, which contained entries showing his arrivals into and departures from India.
Taken together, these documents supported the taxpayer’s claim that he was a non-resident during the relevant period and was working abroad.
Foreign tax return or TRC cannot by itself decide Indian taxability
The ITAT specifically disagreed with the approach of treating the absence of foreign tax documents as sufficient reason to reject the taxpayer’s explanation.
The Tribunal observed that whether the taxpayer had paid tax in another country was not, by itself, a ground for treating income earned abroad as taxable in India. It also said the absence of a foreign tax return, TRC and proof of foreign tax payment could not be used to reject the claim when the taxpayer had produced other evidence showing his non-resident status and foreign employment.
The Tribunal noted that the NRE account showed that the taxpayer had received the salary in US dollars, while the passport and employment documents provided evidence regarding his residence and place of work.
It therefore found that the assessment order was not in accordance with the law.
ITAT did not completely delete the salary addition
The ruling, however, does not mean the taxpayer has received a final exemption from tax on the salary.
The ITAT set aside the assessment and sent the matter back to the AO for fresh adjudication. It specifically directed the AO to consider the taxpayer’s passport entries and NRE account details while deciding the issue.
The Tribunal also directed that the AO should decide the matter without insisting on the foreign tax return, TRC and foreign tax-payment details as a prerequisite for considering the taxpayer’s claim.
The appeal was therefore allowed for statistical purposes, rather than resulting in a final deletion of the salary addition.
What does this mean for NRIs and Indians working abroad?
The ruling highlights an important distinction for non-residents. The account into which salary is credited is not, by itself, enough to determine the taxability of the underlying salary.
In this case, the Tribunal considered the taxpayer’s residential status, employment documents, place of work, passport records and bank statements before directing the AO to reconsider the tax treatment.
This also means that taxpayers working abroad should maintain documents that establish their employment and residential status. These could include employment or assignment documents, payslips, passport travel records and relevant bank statements.
At the same time, the ruling should not be read as a blanket rule that any salary credited to an NRE account is tax-free in India. The ITAT’s direction was based on the particular facts and evidence in this case, and the assessment has been remanded for a fresh decision.
The key issue remains the taxpayer’s residential status and the circumstances in which the income was earned and accrued, rather than simply the fact that the money eventually reached an Indian bank account.