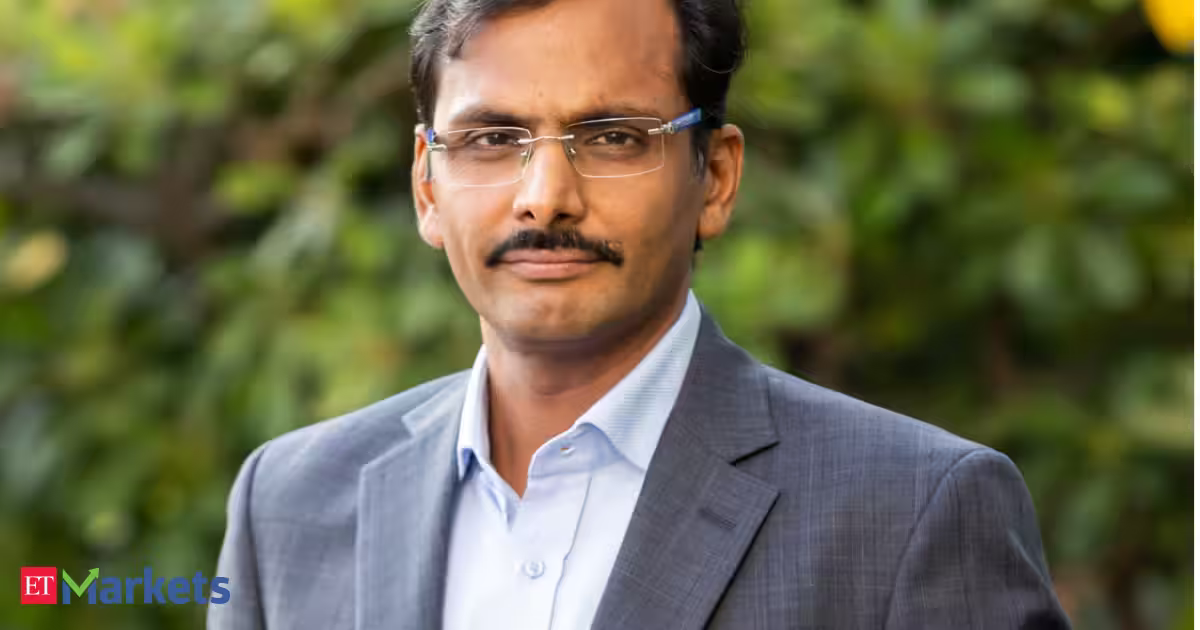
SEBI’s new PMS framework could potentially double industry size over time: APMI Chairman Vikas Khemani
Vikas Khemani, Chairman of the Association of Portfolio Managers in India, believes these changes could potentially double the size of the PMS industry over time.
He says the ability to combine direct mutual fund plans, ETFs, index funds and SIFs with customised portfolio management could bring a much wider affluent investor base into the PMS ecosystem.
In an interaction with Kshitij Anand of ETMarkets, Khemani also discusses the growing role of global diversification, greater use of derivatives, the proposed independent fund-manager framework and why investors should look beyond one-year returns to assess risk, drawdowns and consistency. Edited Excerpts –
Q) You called PRIM a significant step forward for the PMS industry. What is the biggest structural change this introduces for portfolio managers and investors?
A) The biggest structural change is that ‘PRIM’ broadens the definition of portfolio construction. Portfolio managers can now use direct mutual fund plans, ETFs, index funds and SIFs to build customised portfolios, rather than being largely centred around direct securities.

This opens up an opportunity for all mutual fund distributors and independent financial advisors to take PMS route to move from advisory to management.
For investors, this creates access to professional portfolio construction at a lower entry point of ₹25 lakh. It also allows managers to combine different investment vehicles based on the investor’s objectives, risk profile and time horizon. In that sense, PRIM meaningfully widens the scope for the industry.
Q) With PRIM lowering the entry point to ₹25 lakh and the investment universe expanding, do you expect the PMS industry to become significantly larger over the next three to five years?
A) The framework certainly creates the conditions for the PMS ecosystem to expand. Lowering the entry point to ₹25 lakh brings the offering within reach of a broader affluent investor base.
Entire advised MF investment can come within the scope of the industry, which potentially could double the size of industry over time.
Q) PMS managers will get greater flexibility in exchange-traded derivatives, with exposure allowed up to 1.25 times client AUM. What additional risk-management responsibilities does it create?
A) With this manager will be able to use derivatives for hedging or return enhancement. The 1.25-times framework should not be viewed simply as an avenue to increase leverage.
It gives managers another tool for hedging, portfolio construction and efficient exposure management. Strong internal risk frameworks and appropriate suitability assessment will be critical.
Q) SEBI is also enabling PMS managers to invest in foreign securities, including overseas equities, debt, REITs, mutual funds, ETFs, index funds and foreign government debt. How important is global diversification becoming for Indian PMS portfolios?
A) As the prosperity and wealth in the country increases, needs of the investor do change. Global diversification is becoming increasingly needed for some of the investors.
The ability to access overseas equities, debt, REITs, mutual funds, ETFs, index funds and foreign government securities gives portfolio managers another tool to access & diversify sources of return.
It can also help portfolios gain exposure to sectors, companies and markets that may not be adequately represented in India. However, global allocation should remain driven by the client’s objectives, risk profile and overall asset allocation, rather than simply by the availability of overseas opportunities.
Q) SEBI has proposed the concept of Independent Fund Managers, who can manage and operate client portfolios in association with a registered portfolio manager. How could this change the PMS industry structure?
A) The independent fund-manager framework could make the PMS ecosystem more open to specialised investment talent.
It allows an investment manager with a differentiated strategy and client base to manage money without bothering about operations and compliance burden within the regulatory and operational infrastructure of a registered portfolio manager.
The registered portfolio manager retains regulatory accountability, while the independent manager can focus more closely on investment management.
Over time, this could encourage more specialised strategies and potentially lower the barriers for experienced investment professionals to build businesses, while maintaining an appropriate regulatory framework and investor safeguards.
Q) With mutual funds, SIFs, PMS, AIFs and wealth-management products increasingly overlapping in terms of the investor base, where do you see PMS’s distinct role in the Indian wealth-management ecosystem?
A) PMS’s core distinction is personalisation. Mutual funds and SIFs are pooled vehicles with defined mandates, while PMS manages the portfolio at an individual client level.
This allows greater customisation around asset allocation, risk tolerance, liquidity requirements, tax considerations and investment preferences.
As the ecosystem evolves, there will naturally be some overlap between products, but that is healthy for investors because it creates more choice.
PMS should differentiate itself through the quality of portfolio construction, transparency, alignment with client objectives and the ability to deliver genuinely personalised investment solutions.
Q) Should the industry move towards greater emphasis on risk-adjusted returns, drawdowns, consistency and portfolio behaviour rather than just one-year performance?
A) Absolutely, the conversation around performance needs to become more holistic. A one-year return tells only one part of the story.
Investors should also evaluate the risk taken to generate that return, drawdowns, consistency across market cycles, volatility and how the portfolio behaves during periods of stress.
For PMS in particular, where portfolios are customised, the quality and consistency of the investment process are important alongside headline returns.
As the industry matures, I believe greater emphasis on risk-adjusted performance and long-term portfolio behaviour will lead to more informed investor decisions and a healthier investment ecosystem.
(Disclaimer: Recommendations, suggestions, views, and opinions given by experts are their own. These do not represent the views of the Economic Times.)