Closing an unused credit card? Experts explain how it can affect your credit utilisation
An unused credit card can seem an unnecessary burden. Especially with its credit-related features and the risk of getting lost, particularly if it is sitting in your wallet, without being used.
Still, it is important to acknowledge that closing a credit card is not always a straightforward financial cleanup. This is because the decision can affect your available credit, i.e., borrowing potential and, in some cases, even harm your credit score.
This write-up is dedicated to discussing the implications of closing your credit card and the important aspects to consider before proceeding with such a move.
Closing an unused credit card can raise credit utilisation
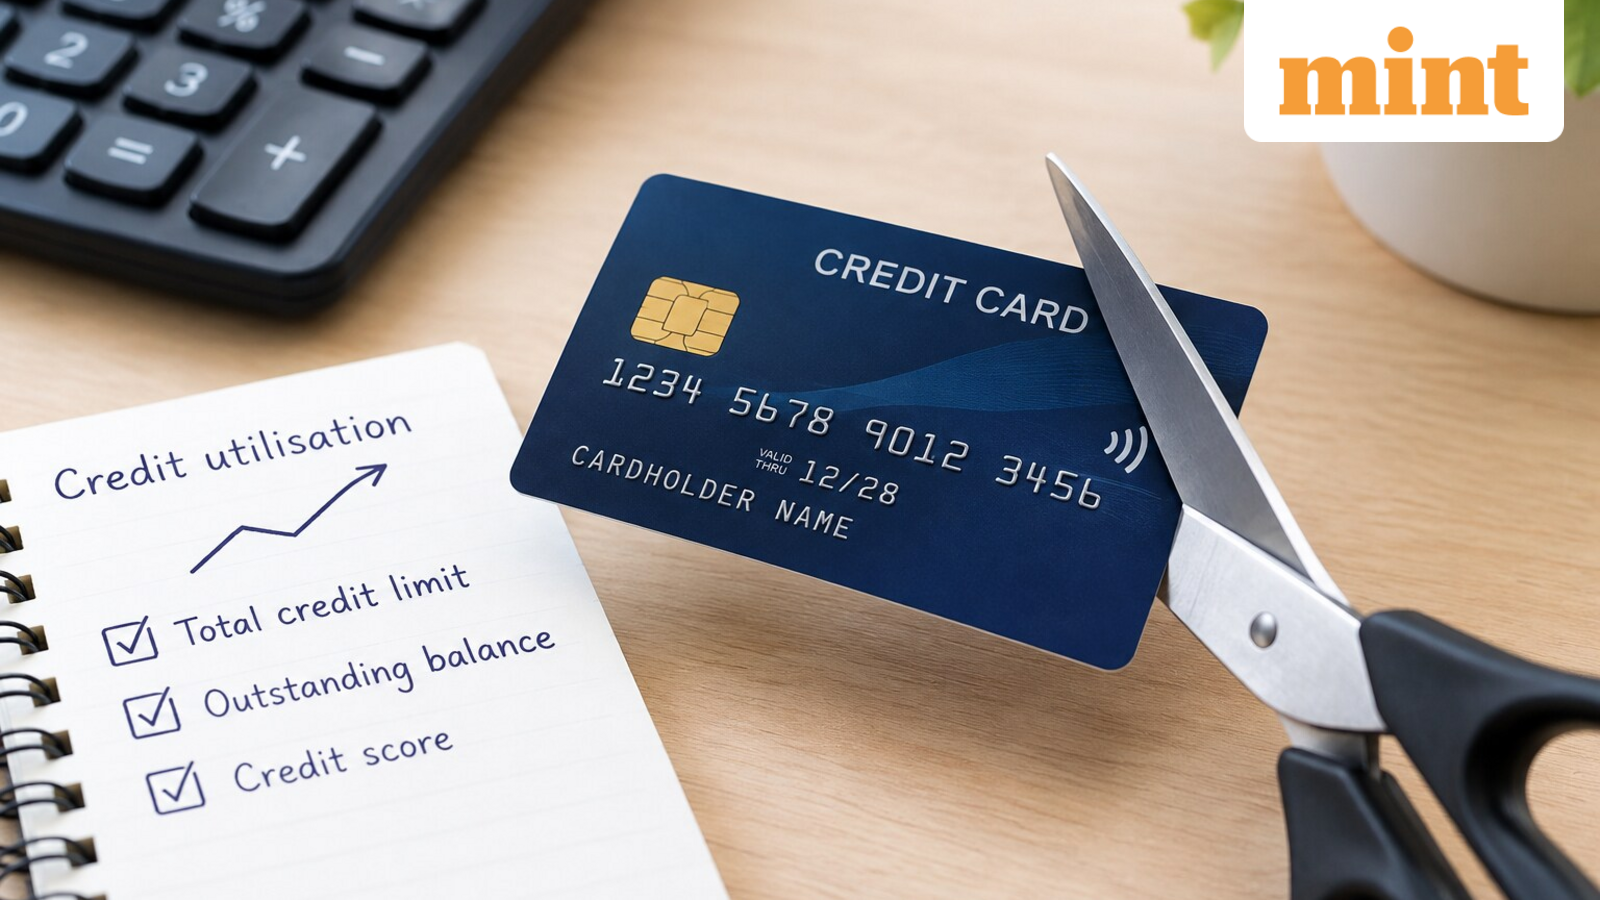
This is the primary aspect that needs careful consideration. Credit utilisation, to put it simply, is the percentage of your total available credit that you are currently using. For example, if your cards have a combined credit limit of ₹5 lakh and your total outstanding balance is ₹1 lakh, then your current overall credit utilisation is 20%.
Now, when you close one of your credit cards, it will reduce your total available credit limit. Furthermore, if your outstanding balances remain unchanged, this can drive your utilisation ratio higher.
Lower utilisation is generally viewed more favourably by lending institutions and credit-scoring models, although there is no universal threshold or a rule that guarantees a particular score. Generally, a 30% credit utilisation level is used as a rule of thumb, rather than an inflexible hard cut-off. Let us understand this with a simple example:
|
Before closing the card |
After closing the card |
|---|---|
| Total credit limit: ₹5 lakh | Total credit limit: ₹3 lakh |
| Outstanding balance: ₹1 lakh | Outstanding balance: ₹1 lakh |
| Utilisation: 20% | Utilisation: 33.3% |
Raj P Narayanam, Executive Chairman, Zaggle, explained this in detail, stating, “Closing an unused credit card feels like financial housekeeping, but it can quietly damage your credit profile. It reduces your total available credit limit, pushing your utilisation ratio higher, and if it is your oldest card, it shortens your credit history, both of which are key scoring factors. The better approach is to keep the card alive with one small transaction every few months and pay it in full. If an annual fee is the concern, negotiate a waiver or downgrade to a lifetime free variant. The card you don’t use may be doing more work for your credit score than you realise.”
When should you consider closing an unused card?
Therefore, keeping a credit card open may sometimes make more sense, especially when it has no annual fee, and it can be managed responsibly. Still, closing it may be worth considering if the card carries a high annual fee, offers nearly negligible or poor benefits, or poses a risk of overspending.
Adhil Shetty, CEO, BankBazaar, added to the aspect in detail, stating, “Retaining an unused credit card is often a much more prudent financial decision than closing it. Cancelling a card reduces your total available limit, which can immediately increase your credit utilisation ratio above the recommended thirty per cent. A higher ratio lowers your credit score, making your future borrowing more expensive. Unless the card has high annual fees, keeping it active with minor, responsible use helps you maintain a strong credit history and supports your long-term borrowing capacity.”
Hence, before closing a credit card, borrowers should check their other card limits, outstanding balances, annual fees, day-to-day usage and whether the card is among their oldest accounts. In case the credit card is retained, occasional small spending followed by full repayment can help in keeping it active and working efficiently.
It is also important to keep in mind that blocking or deactivating a credit card is not the same as closing the card account. This is because closure of the card terminates its relationship with the issuer, and subject to the settlement of dues, the closure request has to be honoured within 7 working days.
In summary, before considering closing a credit card, it is wise to consider all associated factors. It is also prudent to seek professional advice from a certified financial advisor about the associated risks, pros and cons. Furthermore, the decision should consider its fees, benefits, spending discipline and the impact its credit limit could have on your overall credit utilisation.