Back in 2016, French insurance giant Axa (Paris: CS) was known for its complexity. The majority of the company’s earnings came from its life insurance and long-term savings business, the health of which was tied directly to interest rates. That began to change under CEO Thomas Buberl, who took over the group in 2016. Buberl’s vision for the company was simple. The new boss wanted to turn Axa into a leading global insurer in the “short-tail”, relatively capital-light business of property and casualty insurance (P&C).
One of the main issues with life insurance is its “long tail” business – once the insurer has written the life insurance or annuity policy, it’s stuck with the contract for decades, even if it becomes unprofitable. As a result, regulators tend to demand that these firms hold high levels of capital reserves to meet upcoming liabilities and unforeseen developments.
How Axa freed up billions in capital
One of Buberl’s first moves was to carve off its US life-insurance arm, Axa Equitable, which freed up billions of dollars in capital for the group to go shopping. Almost as soon as the company announced the transaction, it launched an offer for XL Group, a leading global P&C insurer. Axa paid $15.3 billion for its peer and was instantly catapulted into the ranks of the world’s largest P&C insurers. As part of its Vision 2020 growth plan, management continued to exit non-core businesses, de-risking the group’s exposure to highly volatile and loss-making segments of the global insurance and reinsurance market and cutting costs.
Try 6 free issues of MoneyWeek today
Get unparalleled financial insight, analysis and expert opinion you can profit from.
Start your trial
Sign up for MoneyWeek’s free twice-daily newsletter.
Join more than 165,000 subscribers and keep yourself informed with latest financial news, insights and expert analysis to help you understand what really matters when it comes to your finances.
Join more than 165,000 subscribers and keep yourself informed with latest financial news, insights and expert analysis to help you understand what really matters when it comes to your finances.
As a result, the group’s revenue mix has changed markedly since 2026. In 2016, before the transformation began, the group reported total revenue of €100 billion, with 50% coming from life and health insurance, and net income of €5.8 billion. By 2022, revenue had fallen 34% to €66.6 billion. However, net income fell just 13% to €5 billion.
Around this time, the group also started to benefit from the dramatic upswing in global insurance and reinsurance prices. Starting around 2019, a combination of inflation and losses has pushed insurers to raise insurance prices globally to offset the added cost of claims.
At the same time, higher interest rates have boosted the returns insurers can earn on the investment portfolios they hold to back up underwriting. Thanks to this double tailwind, insurers have reaped the benefits. Axa’s combined ratio, a measure of underwriting profit, fell to just 90.6% in its 2025 financial year, from 99.5% in 2020. Anything below 100% signifies an underwriting profit while anything above signifies a loss. Thanks to this tailwind, Axa’s net income rose to €9.8 billion in 2025, on a total revenue of €75 billion. Of that total, €58 billion comprised revenue from P&C underwriting.
The company’s next move was to sell its asset-management business. Axa sold this division, Axa Investment Managers (Axa IM), to BNP Paribas for €5.4 billion – 15 times earnings at the time of the deal. The combination of Axa IM and BNP Paribas created an asset manager with total assets under management of €1.5 trillion, giving it the scale to compete in the increasingly competitive asset-management market. Axa immediately gave the bulk of the proceeds from this deal back to shareholders via a share buyback.
Axa’s new plan for growth
Axa has changed completely since 2016 and, on 15 September, the group published its new plan for 2027-2029. The new plan builds on the work management has done over the past decade to get the business to where it is today, and the focus is earnings growth. Management wants Axa to reach earnings growth of 7% to 9% on a compound annual basis over the next three years, above the top end of the 6% to 8% target in the previous plan.
To do this, analysts believe the company will have to broaden its base in Europe, notably in the small and medium-sized enterprise sector, while seeking up to €7million a year in cost savings. Overall, analysts at investment bank Berenberg believe cost savings (mostly from AI) will add 1% a year in earnings across the group, a significant figure.
Management is also forecasting higher cash generation from the group’s subsidiaries. The plan is to generate €25 billion of cumulative cash over the three-year period, up from €21 billion in the 2024-2026 period. A good chunk of this will flow straight back to investors. Berenberg has the group returning €5.4 billion in 2027 and €5.8 billion in 2028, with the stock trading at a 5.8% dividend yield. Buybacks between 2024 and 2028 could shrink the share count by more than 10%. The total shareholder yield, including dividends and buybacks, is pencilled in at 7.8% for 2027 and 8.4% for 2028.
(Image credit: Future)
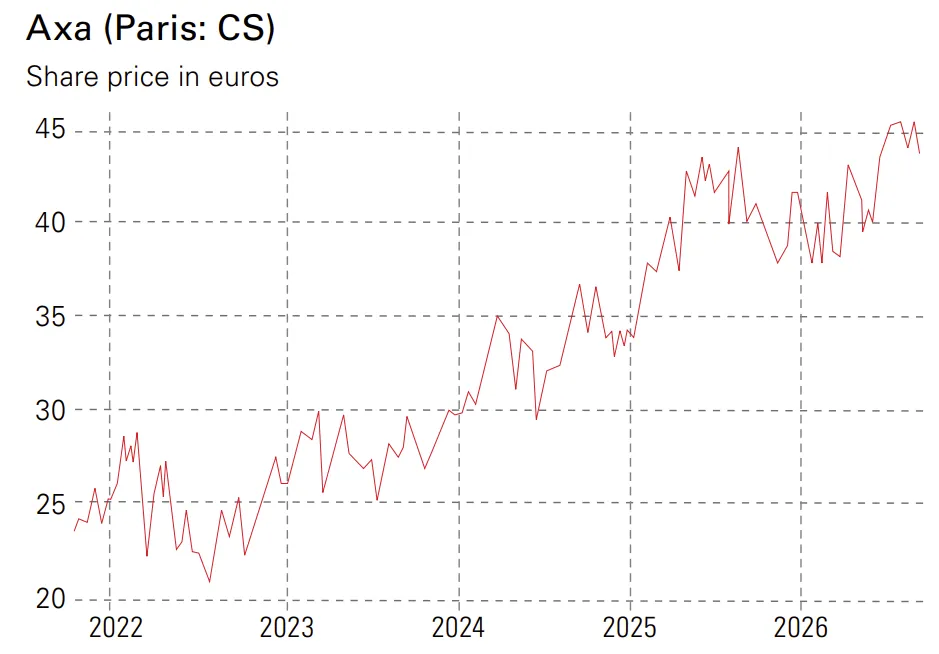
Based on the bank’s estimate of future earnings growth, Axa shares are trading at a forward price-to-earnings (P/E) ratio of eight and a price-to-book ratio (P/B) of 1.59. That looks cheap compared with the group’s earnings outlook and plans to return cash.
There is, of course, risk. A soft insurance market, where prices start to fall, could wipe out growth across the business, and a jump in losses could vaporise profit and force the group to postpone returning cash. All insurers face similar risks, which is why they generally carry a lower rating than the rest of the market.
In Axa’s case, however, its rating seems too low. Indeed, because Axa’s insurance policies are short-tail and reprice every year, the group could quickly adjust to a new environment. As one of the largest players in the global P&C and health-insurance market, Axa shares are worth a closer look at their current valuation.
This article was first published in MoneyWeek’s magazine. Enjoy exclusive early access to news, opinion and analysis from our team of financial experts with a MoneyWeek subscription.
Quadrant manages the scheme and oversaw its refurbishment on behalf of a Korean institutional investor. CRE Herald Market analysis, deal insights, and sector research trusted by fund managers, asset managers, and senior executives. Subscribe Now Already have an account? Log in
Previous articlePan-European commercial property…
Actress Hayden Panettiere has died at the age of 36 after being found unresponsive at an apartment in South Carolina. The “Ice Princess” star died at Judson Mill Lofts in Greenville, SC, on Aug. 16, just five days before what would have been her 37th birthday. Her father, Alan Lee “Skip” Panettiere, confirmed the devastating…
NAB bumped rates across its fixed home loan line up by up to 0.4% p.a. on Friday, amid mounting expectations the Reserve Bank’s February meeting could deliver a hike. Unemployment figures released on Thursday showed the jobs market strengthened in the month of December, with the jobless rate falling to 4.1% – a potential warning…
On Friday, Deriv announced that it has launched its exclusive Derived Indices directly on TradingView, allowing traders to connect their Deriv account and analyse, place, and manage trades without leaving the charting platform. The integration covers Deriv’s full range of Volatility, Crash/Boom, Jump, and Step Indices, with TradingView handling the charting and trading interface while…
(RTTNews) – Spectral Medical Inc. (EDT.TO), a late-stage theranostic company, on Friday announced updates regarding its 100-day meeting with the U.S. Food and Drug Administration (FDA) for Toraymyxin in treating sepsis. Sepsis is a life-threatening illness defined by the entry of bacteria into the blood. Treated with a heavy dose of broad-spectrum antibiotics, treatments often…