Income tax calendar October 2026: ITR, TDS, Form 141 and other deadlines to know
October 2026 has several income tax compliance deadlines for taxpayers, employers, and specified entities. While some dates apply only to specialised taxpayers, others relate to routine TDS reporting and payments.
This year, taxpayers also need to keep in mind both the Income-tax Act, 1961, and the Income-tax Act, 2025. Here are the key October deadlines to keep track of.
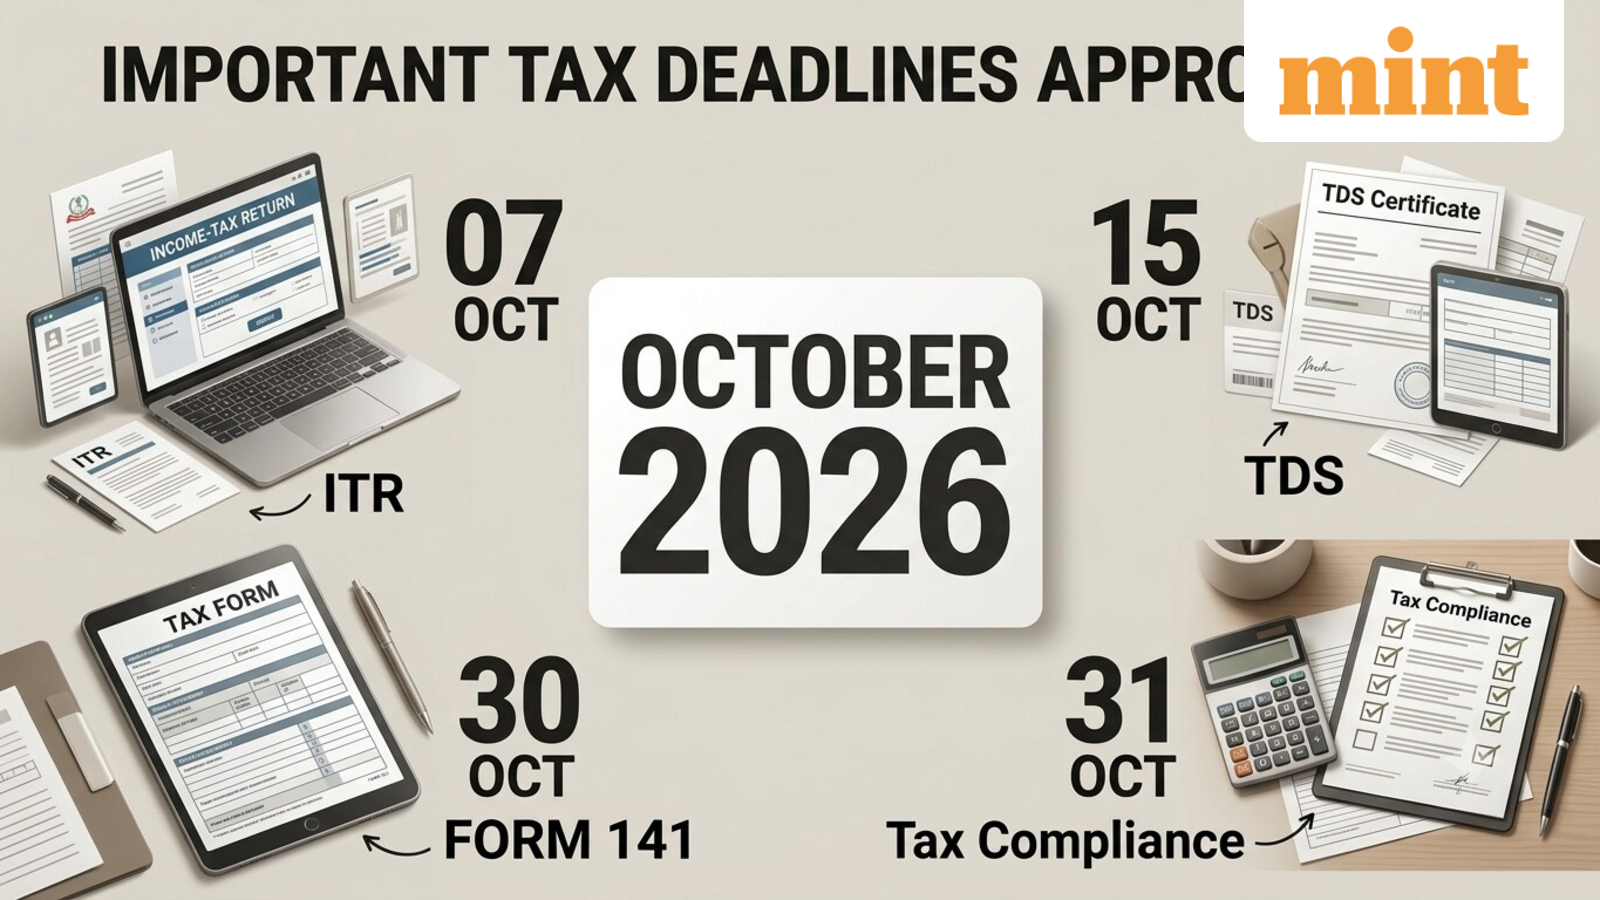
October 15: TDS certificates and specified statements
- A TDS certificate in Form 132 is due on 15 October for tax deducted in August 2026 for tax deducted under section 393(1).
- Form 147 is due from authorised dealers for reporting specified remittances made during the quarter ended 30 September 2026.
- Form 148 is due from specified IFSC units for reporting relevant remittances for the quarter ended 30 September.
- A stock exchange must also furnish Form 1 for September 2026 in respect of specified client code modifications.
These are largely compliance requirements for specified deductors, intermediaries and entities rather than routine filings for salaried taxpayers.
October 30: Form 141 for certain TDS payments
Form 141 is an important new compliance form under the Income-tax Act, 2025. It is a consolidated challan-cum-statement for certain TDS deductions under section 393(1).
October 31: ITR deadline for tax-audit cases
The most important 31 October deadline for many taxpayers is the income-tax return (ITR) filing deadline for AY 2026–27. This applies to taxpayers whose accounts are required to be audited but who are not covered by transfer-pricing provisions.
- Form 138 – TDS statement for salary: Employers responsible for deducting TDS from salaries must file the quarterly TDS statement for the quarter ended 30 September 2026.
- Form 143 – TCS statement: Persons responsible for collecting tax at source under section 397(3)(b) of the Income-tax Act, 2025 must file the quarterly TCS statement for the quarter ended 30 September.
- Form 144 – TDS on payments to non-residents: A quarterly TDS statement is required for specified payments other than salary made to non-residents during July-September 2026. This is under the Income-tax Act, 2025.
- Form 142 – VDA transactions: An exchange dealing with transfers of virtual digital assets (VDAs) must furnish the quarterly statement of tax deposited for the July-September quarter under section 393(1) of the Income-tax Act, 2025.
- Form 3CEB – transfer pricing: Taxpayers covered by section 92E of the Income-tax Act, 1961 must furnish the accountant’s report in Form 3CEB for international transactions or specified domestic transactions. This deadline is particularly relevant because such taxpayers have their ITR deadline on 30 November 2026.
- Section 44AB audit report for transfer-pricing cases: Where a taxpayer is also subject to section 92E, the applicable audit report under section 44AB is due by 31 October, one month before the 30 November 2026 ITR deadline.
- Form 10E – salary arrears: An employee claiming relief under section 89 of the Income-tax Act, 1961, for salary received in arrears or advance may need to furnish Form 10E by the applicable ITR due date.
- Form 10BA – rent deduction: Taxpayers claiming a deduction under section 80GG for rent paid for residential accommodation may need to furnish Form 10BA, where applicable.
- Other specialised filings: Other specialised filings due on 31 October include forms and reports related to deductions, exemptions, and special tax provisions under sections 80JJAA, 80LA, 80QQB, 80RRB, 115AD, 115BBF, 115JB, 115JC and 10(4D), among others.
Disclaimer: This is only for informational and educational purposes. Please consult a qualified expert for the latest laws and regulations.