IRDAI proposes new motor insurance rules: What could change for new car buyers
Buying motor insurance could change significantly if IRDAI’s proposed distribution reforms take effect. The regulator wants customers buying a new vehicle to be given a clearer option to purchase insurance through digital platforms, while also proposing changes to the way motor dealers distribute policies and earn commissions.
The proposals come as IRDAI’s data shows a sharp increase in motor insurance commissions. Motor insurance premiums grew by around 34% between FY23 and FY25, while commissions increased by around 259%, according to the regulator’s consultation paper on “Reforms for Recalibrating Economics of Insurance Distribution.”
Motor insurance commissions have risen sharply
IRDAI said the average commission rate in motor insurance was around 24% in FY25, although the range varied from 13% to 50%.
OEM brokers and Motor Insurance Service Providers (MISPs) together accounted for around 30% of the motor insurance market and received an average commission of 24%, with the maximum going up to 31%.
In FY25, these distributors generated around ₹29,000 crore in premiums and received nearly ₹7,050 crore in commissions, according to the consultation paper.
The regulator has also highlighted differences in commissions across motor insurance products and distribution channels.
For new vehicles, OEM brokers received an average commission of 27%, while MISPs received around 38%. For old vehicles, MISPs received an average commission of 12%.
IRDAI has classified third-party insurance for new vehicles as a “nil-effort product”, since vehicle registration requires evidence of insurance. It has similarly described own-damage and comprehensive insurance for new vehicles as low-effort products.
New-car buyers could get a digital option
A key proposal concerns where customers can purchase motor insurance.
IRDAI has proposed that motor insurance products for both new and old vehicles should be available on Market Infrastructure Institution (MII) platforms such as Bima Sugam.
The regulator has also proposed specific requirements for motor dealers operating as Insurance Distribution Entities (IDEs) or Points of Sales Persons (PoSPs).
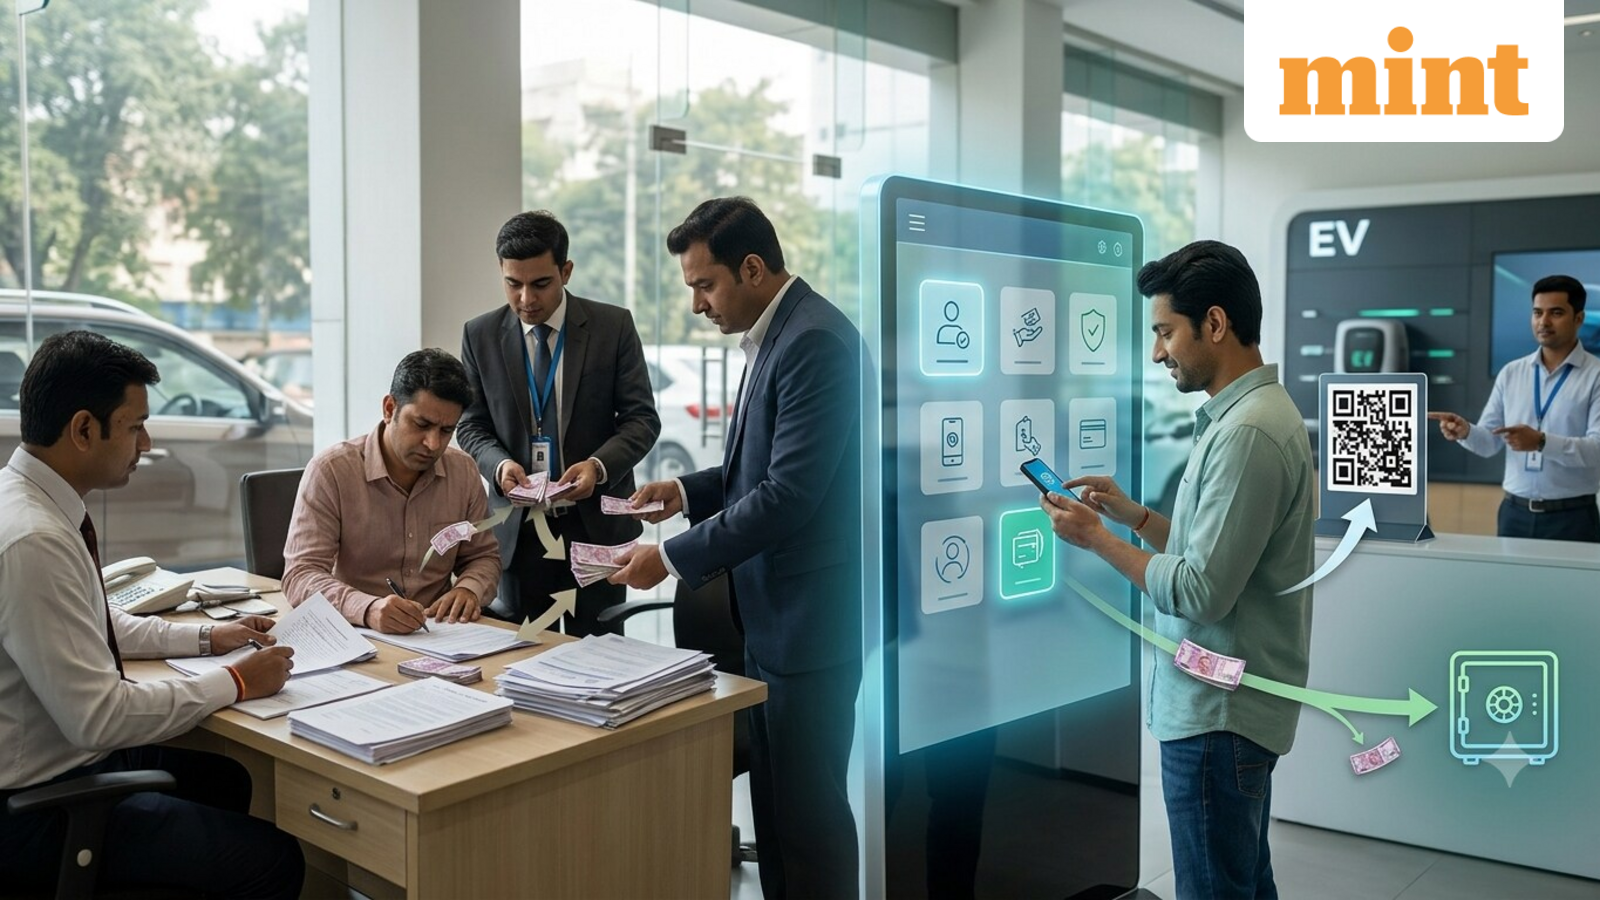
For customers buying new vehicles, dealers would have to prominently display an option to purchase motor insurance through the MII platform, including a QR code through which customers can access the platform. They would also have to make new-vehicle customers aware of this option.
The proposal would therefore introduce a formal digital purchase option into the new-vehicle insurance process.
For not-for-profit platforms established by all or a group of insurers, IRDAI has proposed that the platform fee should not exceed 5% of the premium, with the fee intended to recover platform costs.
What happens to motor dealers?
IRDAI has proposed bringing motor dealers into a more defined distribution framework.
Motor dealers that meet the proposed requirements for an Insurance Distribution Entity would have to register as an IDE if they want to sell insurance. An IDE broker would be able to sell products of multiple insurers.
Other motor dealers that do not meet the IDE structure would have to either tie up as a PoSP of an IDE or become an associate of a single insurer, according to the consultation paper.
The regulator has also proposed restrictions on arrangements between motor dealers, OEMs and insurance distribution entities where such arrangements are against policyholder interests. The paper specifically refers to service-level agreements and performance-linked incentive plans that reward motor dealers for insurance sales.
Buying insurance elsewhere should not affect cashless repair
Another proposed requirement relates to cashless repairs.
IRDAI has proposed that motor dealer IDEs and PoSPs should not deny cashless repair service to a customer on the ground that the insurance policy was not purchased from the dealer.
This proposal sits alongside IRDAI’s requirement for dealers to display the option of purchasing insurance through an MII platform.
The consultation paper also proposes that the customer’s mobile number be shared with the Public Insurance Registry (PIR). The number would have to match the one provided to transport authorities for vehicle registration. PIR would validate the number with the VAHAN vehicle-registration system and send a post-event direct message to the customer regarding fulfilment of the proposed obligations.
Third-party motor insurance could see lower commissions
IRDAI has proposed much lower commissions for mandatory third-party insurance and easy-to-sell motor insurance for new vehicles.
The proposal comes against the increase in the average commission on third-party motor insurance. According to the consultation paper, the average commission rose from 4.3% in FY23 to 22% in FY25.
The regulator’s proposed framework seeks to address what it describes as the economics of motor insurance distribution, including commission levels, distribution structures and the role of digital platforms.
For customers, the most visible proposed change would be the addition of a formal digital route for purchasing motor insurance when buying a new vehicle, alongside the proposed restrictions on how dealers distribute and sell these policies.
These are proposals under consultation, not final rules. IRDAI has invited comments and suggestions from stakeholders before finalising the framework.