The big interview: Why adding more loan officers won’t fix the industry’s cost problem
That math has become harder to ignore the longer the current market drags on. One veteran lender says that instinct has had the industry’s cost structure exactly backward for years.
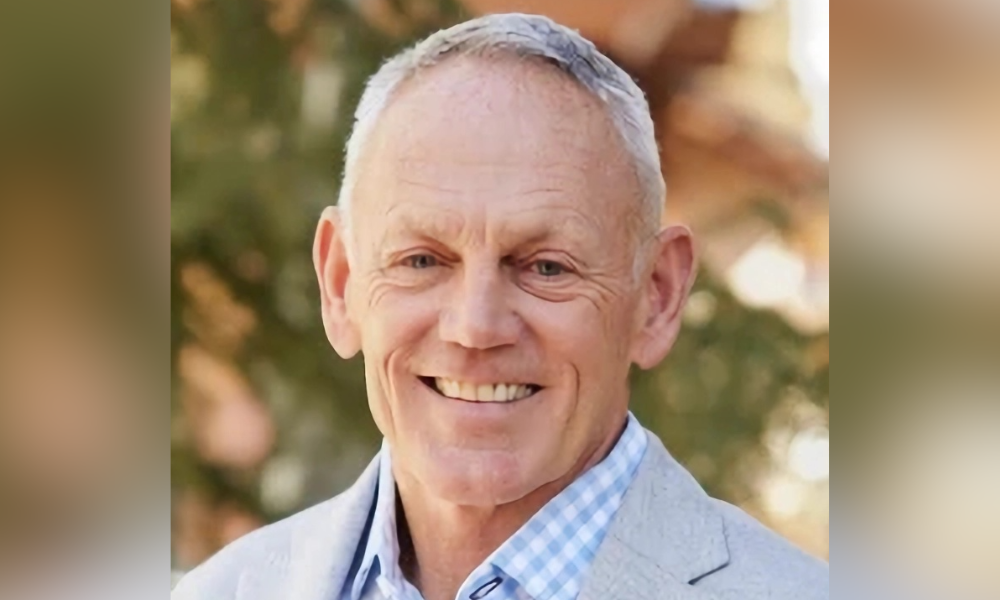
Bill Dallas (pictured top), chairman of Dallas Capital, has spent more than 40 years in the mortgage industry, building and running origination companies through multiple market cycles. He said the industry’s habit of overpaying for dwindling output reminds him of what college athletics is battling with name, image, and likeness payouts (NIL).
“We’re like bad colleges where we want to start buying NIL. We want to start paying like $2 million for an out-of-shape left tackle,” Dallas told Mortgage Professional America. “Why do we want to pay for people doing two loans a month?”
An increase in staffing
Dallas said the comparison to a college is not just a figure of speech. He sees the same bloated support structure that has hammered margins in higher education showing up in mortgage, and it isn’t limited to loan officers alone.
“You need LOAs, processors, and underwriting,” he said. “When the mortgage industry started, like a college, with professors and admin or staff, if you had one production person, you had about a quarter of a person in other staff. Suddenly, if I have one production person, I have two to three staff. And if you go to college, you used to have one professor and no other staff. Now I’ve got like two other staff.”