Have investments across mutual funds, stocks and FDs? Here’s how to ensure your family can find them after your death
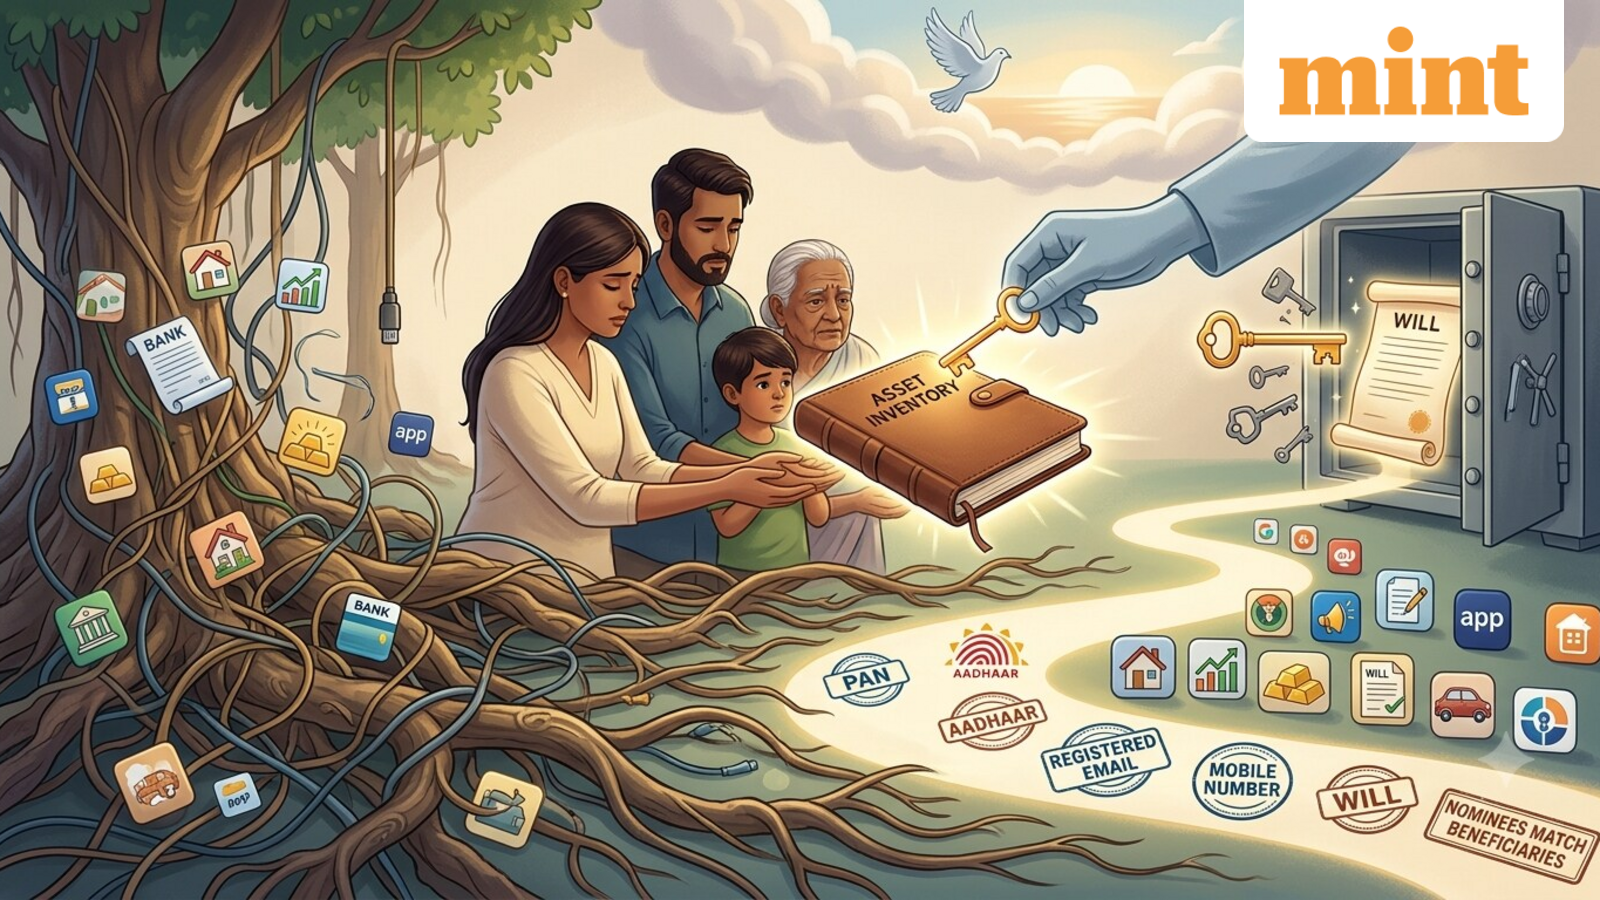
If you have investments spread across mutual funds, stocks, bank deposits, insurance policies and multiple financial apps, your family may struggle to identify all your assets if you die unexpectedly. A simple asset inventory, kept updated and accessible to a trusted family member, can make it easier to locate these investments and begin the transmission process.
Investors should maintain a consolidated asset inventory, preferably in an Excel sheet, covering bank accounts, demat accounts, mutual funds, insurance policies, fixed deposits, investments held through various apps and other financial holdings, said Minisha Rupani, Senior Vice President, Anand Rathi Wealth.
The inventory should include relevant account details, platform names and nominee information and should be kept updated and securely accessible to the family.
Make a consolidated list of all your investments
The first step is to create a single record of your financial assets rather than leaving information scattered across emails, apps, bank statements and physical documents.
The inventory should identify the institutions and platforms where the investments are held, along with account or folio numbers and nominee details. This can help the family establish what the deceased owned before beginning the process of claiming or transferring those assets.
For investors using several brokerage, mutual fund and banking platforms, this becomes particularly important. An investment that is not documented can be difficult for family members to identify, particularly if they do not know which platform or institution holds it.
A nominee alone may not be enough
Investors should not assume that simply naming a nominee will settle the ownership of their assets after death.
“Having only a nominee is not enough,” Rupani said. According to her, a nominee across financial assets is a custodian of the assets, while investors should also have a registered will specifying the beneficiary.
She recommends that the beneficiary mentioned in the will and the nominee recorded against the investments or assets should be the same.
A will becomes particularly relevant when a person has multiple assets, significant wealth or specific wishes about how their assets should be distributed. There is no prescribed age or wealth threshold at which a person must make a will. Any person above 18 can make one, Rupani said.
What your family should know on day one
Consider a person with ₹1 crore spread across 10–15 financial products. If that person dies unexpectedly, the family’s immediate challenge is not necessarily completing every transmission formalities but first finding all the assets.
Rupani said the family should have access to the basic information needed to identify and locate the investments. This should include the person’s PAN, Aadhaar, registered mobile number and email address associated with the investments.
The consolidated asset list should cover bank accounts, mutual funds, shares, bonds, insurance policies, fixed deposits and other investments, along with the relevant institutions, platforms and account or folio numbers. Details of nominees and the will should also be available.
The detailed transmission process can be dealt with subsequently because the documentation and procedures differ across asset classes and financial institutions.
What happens if an investment is never discovered?
Shares or mutual fund investments do not simply disappear if family members are unaware of the demat account in which they are held. They generally remain in the investor’s name and may eventually be classified as unclaimed, subject to applicable rules.
Depending on the type of asset and the period of inactivity, assets may eventually be transferred to the relevant Investor Education and Protection Fund (IEPF) or other prescribed mechanisms, Rupani said.
Investors should look to make it possible for your family to find the money before they have to figure out how to claim it. A regularly updated asset inventory, clear nominee details and a will can help create a roadmap for the family when it is needed most.