Payment Rails Are Connecting Across Borders, but Compliance Is Getting Harder
In November 2025, Brazil’s central bank published a new
licensing framework for anyone offering virtual-asset services connected to
payments in its market. The rules took effect on February 2, 2026, opening a
270-day transition window that runs to October 30, 2026.
London’s trading industry is coming home!
Institutions providing PIX services now face new
authorisation and due-diligence requirements before transacting with
virtual-asset counterparties, and providers that miss the transition deadline
face exclusion from the Brazilian financial system. For some market
participants, the operational impact became apparent well before the full
compliance deadline.
That
is what regulatory drift looks like up close. Global merchants entering
emerging markets tend to treat compliance as a one-time task: integrations
built, legal signed off, problem solved. What the last few years in Brazil,
Colombia and Southeast Asia show is that the rules don’t stay solved.
South America: the PIX Effect and What Comes After
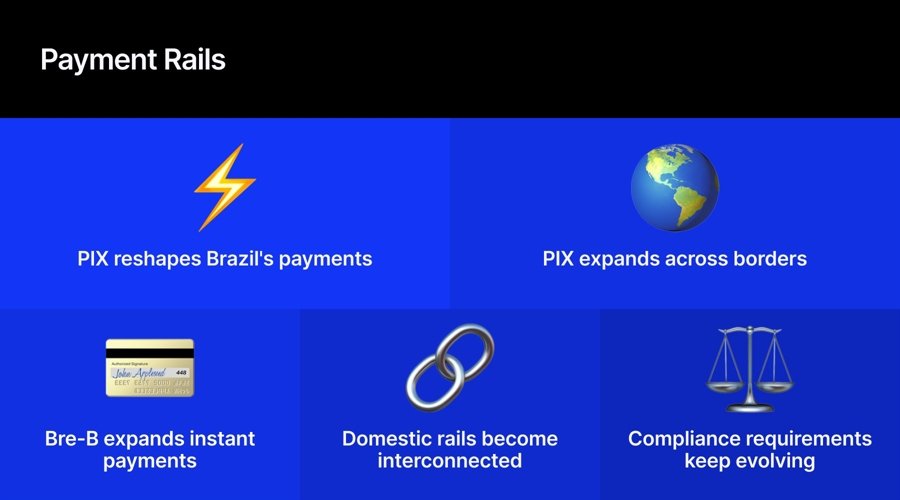
Brazil’s PIX shows how quickly a state-backed instant
payment scheme can remake a market. Since its 2020 launch, it has reached more
than 90% of Brazil’s adult population, overtaken cards as the leading
e-commerce payment method, and kept expanding: recurring payments via PIX
Automático and instalment-like behaviour via PIX Parcelado.
Each addition has
brought new technical requirements and revised participation thresholds for
banks, processors and their merchant clients.
In November 2025, Brazil tightened things further. Three
central bank resolutions gave institutions operating as PIX service providers
until February 2026 to ensure all virtual-asset counterparties were properly
licensed, or face the consequences already described. The deadline arrived with
limited notice for many.
Since early 2026, PIX
has also been operating across borders. Brazil extended the scheme into
Argentina, letting Brazilian users pay Argentine merchants via QR with
automatic currency conversion. What started as a domestic rail now carries
cross-border compliance obligations for anyone operating in the South American
corridor.
It’s an early, single-bank deployment rather than a full scheme
extension, but it signals that a domestic rail can generate cross-border
compliance considerations for providers operating in the corridor.
Colombia is on the same trajectory. Bre-B, Colombia’s
instant payment scheme, launched in 2025 with mandated interoperability from
the start. Whether P2P usage becomes dense enough in 2026 to begin displacing
cards at scale is an open question, but merchants treating Bre-B as an optional
integration are betting on that threshold arriving later than the evidence from
Brazil suggests it will.
Southeast Asia: Six Markets, Six Rulebooks
Southeast
Asia runs the same pattern at greater scale and, currently, with far less
standardisation. Indonesia’s QRIS, mandated by Bank Indonesia, connected 40
million merchants within a few years of launch. Vietnam’s QR transaction volume
grew 62% in 2025 and 151% by value. Thailand’s PromptPay processes over 74
million transactions daily in a country of 72 million people.
These domestic schemes are now connecting to each other, and
that creates its own compliance layer. By late 2025, ASEAN had established 29
cross-border payment linkages: a Thai user paying a Singaporean merchant via
PromptPay by scanning a PayNow code, or someone in Indonesia paying in Malaysia
via QRIS.
Project Nexus, a BIS-led initiative based in Singapore, is building a
multilateral hub to replace this patchwork. Indonesia joined as the sixth
participant in February 2026.
Nexus standardises the plumbing: how payment instructions
pass between national systems. It does not, by itself, harmonise the regulatory
frameworks that sit behind each rail. FX rules, data localisation requirements
and fraud liability stay with each central bank. The pipes become
interoperable; the laws don’t.
The direction of travel is toward greater connectivity. But
more linkages mean a wider compliance perimeter, not a simpler one.
Staying Current
The technical bar for entering these markets has never been
lower. Connecting to PIX or QRIS is table stakes: most providers can
demonstrate they’ve done it. That’s the wrong thing to evaluate. The question
that matters is what happens in month eighteen, when the central bank issues a
new resolution, or a cross-border linkage goes live with a compliance
requirement nobody flagged in the original integration spec.
What that demands from a provider is less about technical
capability and more about presence. Regulatory changes in Brazil, Indonesia or
Vietnam don’t announce themselves in English on a schedule that suits merchant
planning cycles. They emerge from relationships with central banks, with local
legal counsel, and with the payment schemes themselves.
The merchants who’ve navigated this well tend to ask a
different set of questions during provider selection. Not just “can you
connect us to these rails?” but “how did you handle the February 2026
PIX deadline?” or “what’s your process when Bank Indonesia updates
QRIS participation requirements?” The answers reveal whether compliance is
treated as a setup task or an ongoing one.
Integration doesn’t end at go-live. In markets moving at
this pace, it never really does.
This article was written by Maria Uriarte at www.financemagnates.com.