Credit line on UPI: From RuPay cards to pre-sanctioned loans—how it works and what users need to know
UPI users can use certain pre-sanctioned credit lines as a source of funds, allowing eligible customers to make payments through UPI using borrowed money instead of the balance in their bank account.
However, this is not an entirely new facility. RuPay credit cards can already be linked to UPI for eligible merchant payments, while credit-linked UPI products have also been introduced in the market.
The NPCI’s UPI Consolidated Circular released on 18 September has mentioned the framework for using both interest-free and interest-bearing credit lines across UPI.
The circular states that “UPI supports inclusion of pre-sanctioned credit lines as a source of funds” and that credit on UPI will provide a “seamless, UPI-enabled credit lifecycle experience for users.”
What exactly is Credit on UPI?
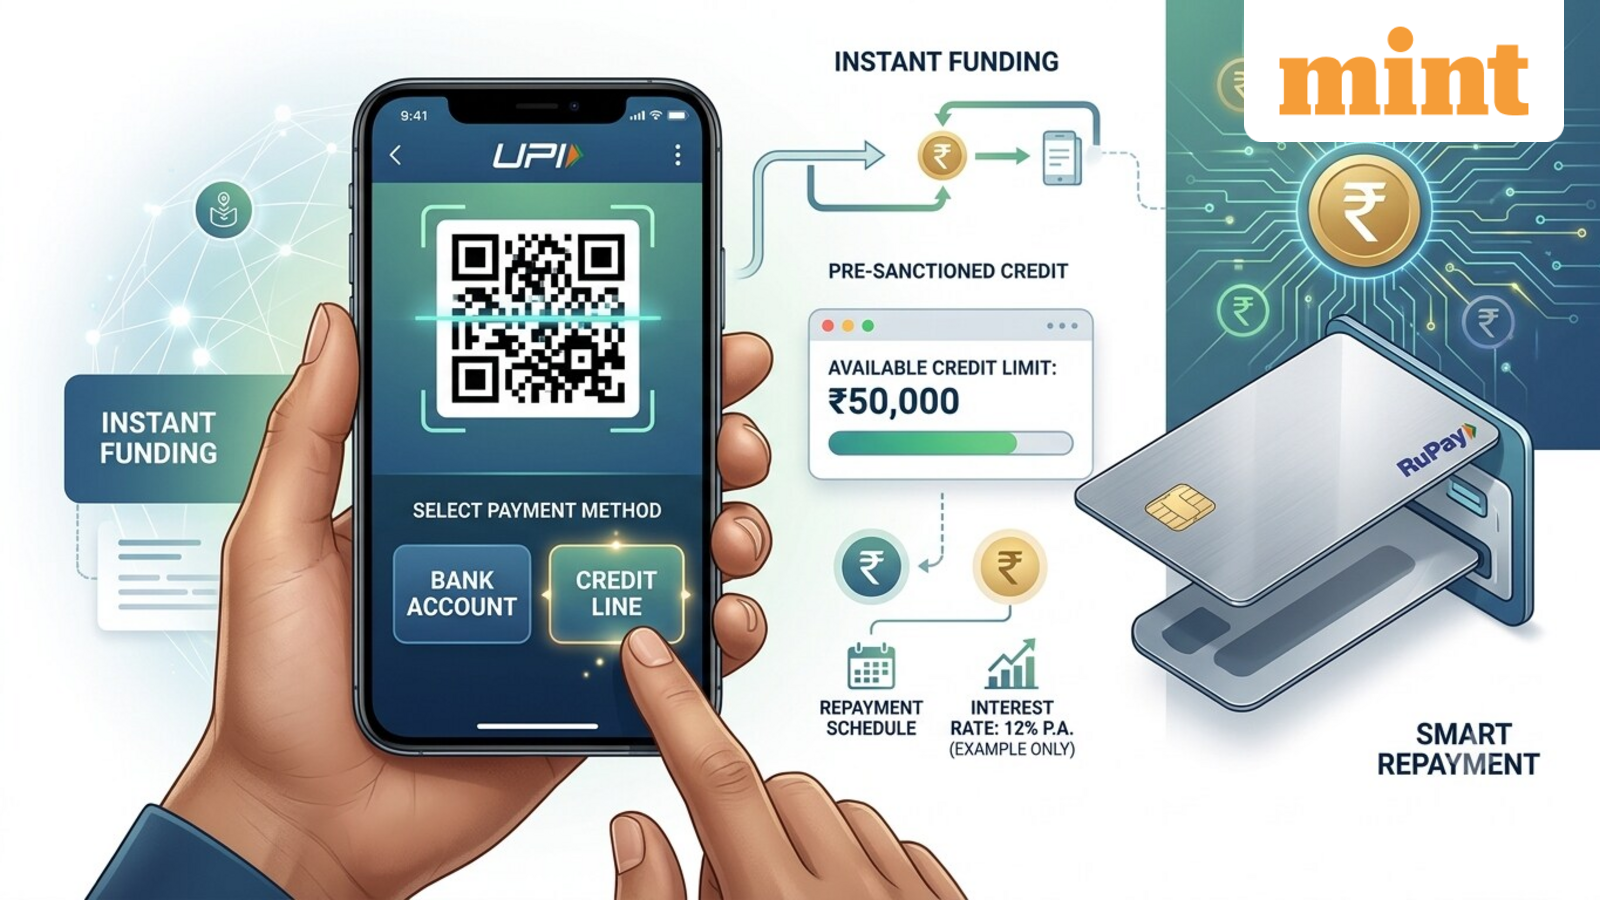
In simple terms, it allows an eligible user to connect a pre-approved credit facility to a UPI app and use it for permitted payments.
For example, suppose your bank gives you a ₹50,000 pre-sanctioned credit line. Instead of first transferring money to your savings account, you may be able to select that credit line while making an eligible UPI payment.
The user will then have to repay the amount according to the terms of that credit facility.
What are the two types of credit lines?
The credit on UPI is divided into two broad categories:
- Interest-free credit line (CLIF): You can use the credit without interest during the interest-free period, provided the entire outstanding amount is paid by the due date.
- Interest-bearing credit line (CLIB): Interest starts accruing from the date of the transaction.
This means users should not assume that every credit on a UPI transaction is interest-free. The cost of borrowing will depend on the specific credit facility.
Where can you use Credit on UPI?
The framework permits credit on UPI to be used across several UPI features, including merchant payments, EMI transactions, UPI AutoPay, and UPI Reserve Pay, subject to the type of credit line and the issuer’s conditions.
However, there are important differences between credit products:
| UPI feature | RuPay Credit Card on UPI | Interest-free credit line (CLIF) | Interest-bearing credit line (CLIB) |
| Merchant payments (P2M) | Allowed | Allowed | Allowed, subject to permitted end use |
| Person-to-person transfers (P2P) | Not allowed | Not allowed | Allowed, subject to permitted end use |
| UPI AutoPay | Allowed | Allowed | Allowed |
| UPI Reserve Pay | Allowed | Allowed | Allowed |
| EMI | Allowed | Allowed | Allowed |
| UPI Lite | Not allowed | Not allowed | Not allowed |
| UPI Circle | Not allowed | Not allowed | Not allowed |
| UPI International | Allowed | Not allowed | Not allowed |
*Source: NPCI’s UPI Consolidated Circular
What is mentioned in the September circular?
“Members shall standardise the account subtype and account reference number (as per the detailed guidelines laid down in the product document) to harmonise the user experience, reducing friction at the point of payment, and enabling scalable adoption of Credit on UPI,” according to the circular.
Members and UPI application providers have been given 15 December 2026 as the deadline for implementation.
The issuer will continue to decide who receives the credit, the applicable terms, permitted uses and whether a transaction is approved.
Disclaimer: This is for informational purposes only. Please visit the official website for the latest updates.