Stocks Mixed as Crude Oil Prices and Bond Yields Rise
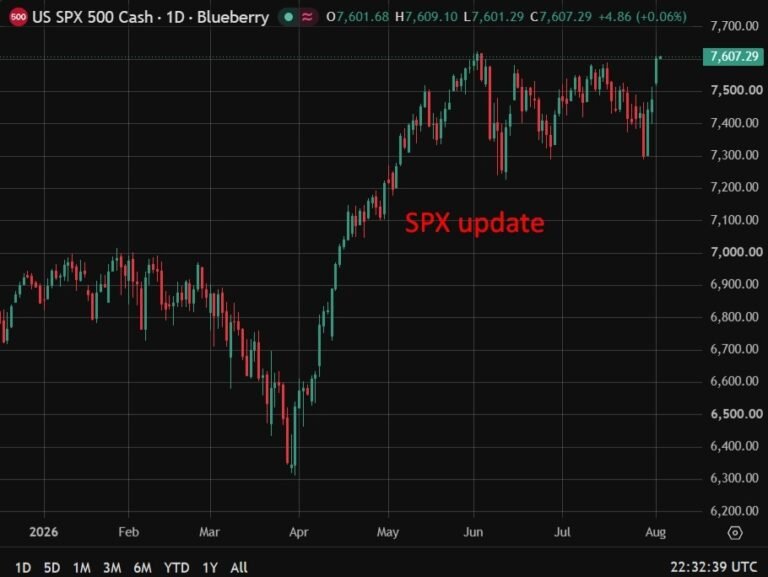
The S&P 500 Index ($SPX) (SPY) is down by -0.03% today, the Dow Jones Industrial Average ($DOWI) (DIA) is down by -0.23%, and the Nasdaq 100 Index ($IUXX) (QQQ) is up +0.20%. December E-mini S&P futures (ESZ26) are down -0.05%, and December E-mini Nasdaq futures (NQZ26) are up +0.17%.
Stock indexes are mixed today, with the Nasdaq 100 posting a 1-week high. Strength in crude oil prices today is boosting bond yields and is weighing on the broader market. WTI crude oil is up more than +1% today, boosting inflation expectations and weighing on market sentiment. The 10-year T-note yield is up +5 bp to 4.99%. However, strength in chipmakers and AI-infrastructure stocks is limiting losses in the broader market and keeping the Nasdaq 100 in positive territory.
Join 200K+ Subscribers:
Find out why the midday Barchart Brief newsletter is a must-read for thousands daily.
Weaker-than-expected US economic news is also bearish for stocks after Aug manufacturing production unexpectedly fell -0.3% m/m, weaker than expectations of +0.3% m/m and the largest decline in 10 months.
Stock volatility today may be higher than usual due to the quarterly event known as triple witching, when equity options, futures, and derivatives expire. According to Citadel Securities, about $7 trillion of options are set to expire today, one of the largest ever. Index rebalancing may also lead to market turbulence, with Bloom Energy, Illumina, and Everpure added to the S&P 500 after the close, while SpaceX will get a weighting boost from a Nasdaq 100 rebalance.
Oct WTI crude oil prices (CLV26) are up by more than +1% today as Middle East tensions continue to disrupt crude supplies. Crude gains are limited on hopes that diplomacy can end hostilities in the Middle East and resume crude flows from the region. Reuters reported that China privately asked Iran to help rein in Houthi militants in Yemen. The militants have attacked energy facilities in Saudi Arabia and advanced toward the Bab-el-Mandeb strait, the chokepoint at the southern end of the Red Sea.
Some crude supplies from the Middle East are getting through, easing supply concerns. On Wednesday, US Energy Secretary Wright said 18 million bbl of crude oil and refined products went through the Strait of Hormuz on Tuesday, easing global supply concerns.
Also, Saudi Arabia said it seeks to return about half the capacity of the East-West pipeline within days following a shutdown last week because of drone strikes. The East-West pipeline, which carries 7 million bpd of crude, was closed late last week after threats from Houthi rebels. The pipeline moves oil away from the Persian Gulf toward the Red Sea, where it can be loaded on tankers. Saudi Arabia told OPEC last Thursday that its crude production in August fell to 6.238 million bpd, the lowest since 1990.
Markets are discounting a 58% chance of a +25 bp Fed rate hike at the next FOMC meeting on October 27-28.
Overseas stock markets are mixed today. The Euro Stoxx 50 is down -1.26%. China’s Shanghai Composite rose to a 1-week high and closed up +0.94%. Japan’s Nikkei-225 Stock Average climbed t a 1-week high and closed up +1.38%.
Interest Rates
December 10-year T-notes (ZNZ6) are down by -8 ticks today. The 10-year T-note yield is up +5.6 bp to 4.986%. T-notes are under pressure today from strength in crude oil prices, which is boosting inflation expectations. Losses in T-notes are contained after US Aug manufacturing production unexpectedly declined, a dovish factor for Fed policy.
European government bond yields moved lower on Thursday. The 10-year German bund yield is up +3.5 bp to 3.512%. The 10-year UK gilt is up +6.8 bp to 5.291%.
The ECB Aug 1-year CPI expectations rose to +3.0% from +2.9% in July, weaker than expectations of +3.1%. The Aug 3-year CPI expectations rose to +2.9% from +2.7% in July, stronger than expectations of +2.8%.
German Aug PPI rose +1.1% m/m and +4.6% y/y, stronger than expectations of +0.6% m/m and +3.9% y/y, with the +4.6% y/y increase the largest in 3.25 years.
ECB President Christine Lagarde said economic growth in the Eurozone is a bit more promising than we thought, and we’re not seeing second-round effects on inflation yet.
UK Aug retail sales ex-auto fuel unexpectedly rose +0.6% m/m, stronger than expectations of a -0.2% m/m decline.
Markets are discounting a 56% chance of a +25 bp ECB rate hike at the ECB’s next meeting on October 29.
US Stock Movers
Software stocks are under pressure today, a negative factor for the broader market. Thomson Reuters (TRI) is down more than -3%, and Intuit (INTU), Oracle (ORCL), Palantir Technologies (PLTR), Workday (WDAY), and IBM (IBM) are down more than -2%. Also, Adobe Systems (ADBE), Datadog (DDOG), Salesforce (CRM), and ServiceNow (NOW) are down more than -1%.
Cybersecurity stocks are weaker today, pressuring the overall market. Palo Alto Networks (PANW) and Cloudflare (NET) are down more than -3%, and CrowdStrike Holdings (CRWD), Fortinet (FTNT), Okta (OKTA), and SentinelOne (S) are down more than -2%. Also, Zscaler (ZS) is down more than -1%.
Chipmakers and AI stocks are climbing today, supporting gains in the broader market. The iShares Semiconductor ETF (SOXX) is up more than +1%. Broadcom (AVGO) is up more than +4%, and Lam Research (LRCX) and SanDisk (SNDK) are up more than +3%. Also, Applied Materials (AMAT) and Seagate Technology Holdings Plc (STX) are up more than +2%, and Western Digital (WDC), KLA Corp (KLAC), Micron Technology (MU), Analog Devices (ADI), and Texas Instruments (TXN) are up more than +1%.
Cryptocurrency-exposed stocks are moving higher today, with Bitcoin (^BTCUSD) up more than +2% after the SEC moved forward with a plan to allow digital versions of securities to start trading in the US. Strategy (MSTR) is up more than +9% to lead gainers in the Nasdaq 100, and MARA Holdings (MARA) is up more than +8%. Also, Coinbase Global (COIN) is up more than +6% to lead gainers in the S&P 500, and Circle Internet Group (CRCL), Bullish (BLSH), Galaxy Digital Holdings (GLXY), and Robinhood Markets (HOOD) are up more than +5%. In addition, Riot Platforms (RIOT) is up more than +4%, and Iren Ltd (IREN) is up more than +2%.
Xenon Pharmaceuticals (XENE) is down more than -25% after it paused enrollment in clinical studies of major depressive disorder and bipolar depression.
Netflix (NFLX) is down more than -4% to lead losers in the S&P 500 and Nasdaq 100 after Wells Fargo Securities downgraded the stock to underweight from equal weight with a price target of $57.
Nucor (NUE) is down more than -4% after forecasting Q3 EPS of $5.55 to $5.65, weaker than the consensus of $5.99.
Macom Technology Solutions Holdings (MTSI) is up more than +3% after BMO Capital Markets upgraded the stock to outperform from market perform with a price target of $335.
Yeti Holdings (YETI) is up more than +1% after Stifel upgraded the stock to buy from hold with a price target of $50.
Earnings Reports (9/18/2026)
AnaptysBio Inc (ANAB) and Rezolute Inc (RZLT).
On the date of publication,
did not have (either directly or indirectly) positions in any of the securities mentioned in this article. All information and data in this article is solely for informational purposes.
For more information please view the Barchart Disclosure Policy
here.
More news from Barchart