Mortgage Rates Today, Friday, September 18: No Change
It’s been a long week, and even mortgage rates are taking a beat today, holding steady with yesterday’s levels.
The average interest rate on a 30-year, fixed-rate mortgage remained at 7.05% APR, according to rates provided to NerdWallet by Zillow. This is unchanged from yesterday and four basis points lower than a week ago. (See our chart below for more specifics.) A basis point is one one-hundredth of a percentage point.
Mortgage rates are pegged to the yield on the 10-year Treasury, and longer-term bond yields are falling back a little. The bond market’s been unhappy with the Federal Reserve’s inaction on inflation, so the Fed hiking the funds rate to fight inflation is welcome news. When bond yields are more chill, mortgage rates are, too.
For more on the ramifications of Wednesday’s Fed meeting and what it could mean for mortgage rates, keep reading below the chart.
P.S.: While the economy never sleeps, markets are closed on the weekends. The rates you see Friday are unlikely to change much (if at all) until Monday.
Average mortgage rates, last 30 days
🤓 Kate on Rates: September 17, 2026
📈 What influences mortgage rates?
A little bit of a side note, but for someone who has such conviction that the Fed’s decisions shouldn’t hang on any particular bits of data, chair Kevin Warsh’s opening remarks at the post-announcement press conference sure made it sound like that data was important.
But anyway.
The bigger news out of the September meeting wasn’t the rate hike that basically everyone expected, it was the potential for additional rate hikes on the way. The Fed released an updated Summary of Economic Projections, where the committee members all shared their anonymized predictions for major metrics. (Except for Warsh, who refuses to participate.)
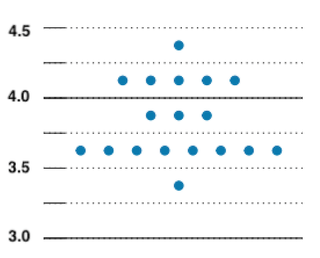
One of the most closely watched is the “dot plot,” where each dot represents an estimate of the appropriate level for the federal funds rate — the overnight borrowing rate that the Fed adjusts — at the end of each year. Looking at the previous round of projections for 2026 versus the ones released Wednesday shows a pretty stark difference, and not just because they had to cram most of the dots into one row in September.
Federal Reserve Dot Plot: June vs. September
Each dot represents an individual estimate for where the federal funds rate should be at the end of 2026.
June predictions
September predictions
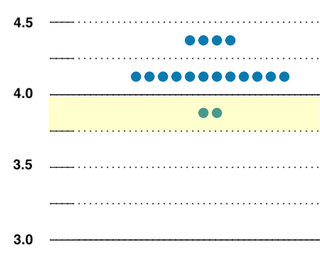
The yellow shading indicates the current level.
Source: Federal Reserve Summary of Economic Projections
Parsing Warsh’s words at the press conference also has folks thinking this isn’t a one-and-done rate hike. (I should also note that this is pretty much exactly what Warsh doesn’t want markets doing. Oh well.) One phrase was quickly singled out: “dose of accommodation.”
This first came up fairly early in his prepared remarks. “I would be hard-pressed to describe broad financial conditions as restrictive,” Warsh said. “This view was widely shared by the committee. So, we removed a dose of accommodation.” He went on to reference the “dose of accommodation” twice more while taking reporters’ questions.
Between the implication of “dose” seeming like it wouldn’t happen just once, Warsh otherwise sounding like he believes the economy is strong and of course, the dot plot, markets are more decisively anticipating one or more additional rate hikes by the end of the year. According to the CME Group’s FedWatch tool, the odds of another 25-basis-point hike in October are roughly 55%, and the odds of a follow-up in December are just under 43%. Those are up from yesterday; a week ago, those numbers were about 42% and 27%, respectively. (Also bear in mind this time a week ago, we had all that August inflation data in hand; the odds were significantly lower just a day prior.)
Like I said above, the Fed getting serious about fighting inflation looks like it’s helping to relieve some of the bond market’s stress that inflation will simply grow unchecked. But in order for the Federal Reserve to try to tame inflation, they’ve got to raise the funds rate. Changes to the federal funds rate ripple out to every corner of the economy, and we’re now potentially looking at a higher for longer rate environment.
While the Fed’s actions, and markets’ reactions to them, are taking some of the upward pressure off of mortgage rates, don’t expect mortgage rates to drop.
Explore mortgages today and get started on your homeownership goals
Get personalized rates. Your lender matches are just a few questions away.
Refinancing might make sense if today’s rates are at least 0.5 to 0.75 of a percentage point lower than your current rate (and if you plan to stay in your home long enough to break even on closing costs).
With rates where they are right now, you could start considering a refi if your current rate is around 7.55% or higher.
🏡 Should I start shopping for a home?
There is no universal “right” time to start shopping — what matters is whether you can comfortably afford a mortgage now at today’s rates.
🔒 Should I lock my rate?
Rate locks protect you from increases while your loan is processed, and with the market forever bouncing around, that peace of mind can be worth it.
🤓 Nerdy Reminder: Rates can change daily, and even hourly. If you’re happy with the deal you have, it’s okay to commit.
🧐 Why is the rate I saw online different from the quote I got?
In addition to market factors outside of your control, your customized quote depends on your:
Even two people with similar credit scores might get different rates, depending on their overall financial profiles.
👀 If I apply now, can I get the rate I saw today?
Maybe — but even personalized rate quotes can change until you lock. That’s because lenders adjust pricing multiple times a day in response to market changes.