Gen H proves it’s possible to grow from scratch and make an influence, says CEO
Gen H is proud of its journey to date, having launched as an innovative lender focused on getting more people into homeownership six years ago.
When Gen H launched, it led on the first-time buyer proposition with a joint borrower sole proprietor (JBSP)-style mortgage. It has since added a New Build Boost, modelled on the Help to Buy equity loan, and interest-only mortgages.
Today, first-time buyers make up most of its business, accounting for 60% of its lending activity.
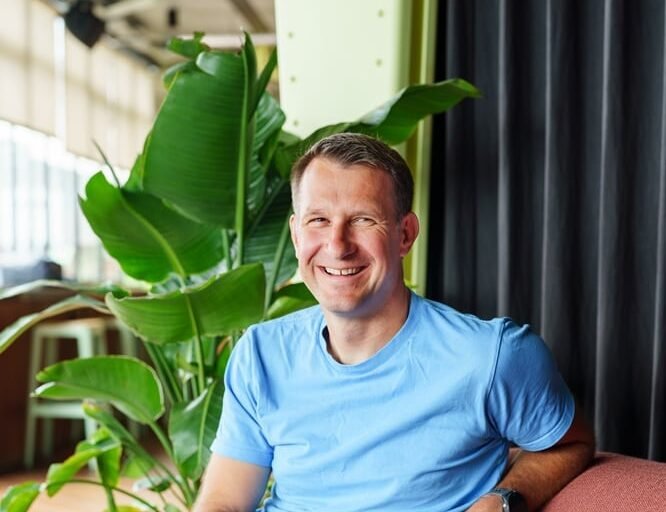
In conversation with Mortgage Solutions, its CEO, Graham McClelland (pictured), said the lender had no ambition to compete with the big six lenders, as they already held their places in the market “reasonably well”.
“We are trying to focus on doing things that are incremental, and typically, the most obvious place to start is with first-time buyers, because you can create a homeowner where there wasn’t one,” he added.
Around a fifth of Gen H’s business is remortgage.
Giving brokers the winning edge
Sponsored by Rely
Where Gen H does want to concentrate, McClelland said, is segments that few or no other lenders operate in, contemplating borrowers with less-than-perfect credit and potentially second charge lending.
“We don’t tend to lend to them today, but I’m very confident in the way that we underwrite and the way that our systems work; we can support a much broader range of people. We want to look to push how we lend to allow more people the opportunity to get a Gen H mortgage,” he said.
Gen H will also leverage relationships with other firms to support its balance sheet, replicating the four existing funding relationships it has with building societies such as Furness and Nottingham. McClelland said he would like the lender to secure at least eight similar arrangements in total.
Observing that lenders were attempting to overcome the slower market with more criteria changes, McClelland said: “For us to solidify our place in the market, in addition to all the things we do, we’ve got to keep ourselves on our toes when it comes to policy and criteria.”
Gen H will focus on “evolution rather than revolution”, shaped by maintaining its service levels and the risk appetite of its funders.
“We have a long list of things we think there’s value in. We’ll prioritise through those based on how we distribute, how we ensure good customer outcomes, how we fund and how we build the product,” McClelland said.
“High-quality lending” and customer satisfaction back the lender’s growth each year, and although 2026 has been “volatile”, McClelland is happy with how the year has played out.
However, he does not expect the volatility in pricing and rates to stop soon, describing the market as “bifurcated”, adding: “There are pockets where things are down and pockets where things are continuing to rise, but it does seem that most of the country is quite flat.”
Making a mark
Whenever a lender does something similar to Gen H, it benefits from residual business, McClelland said.
He welcomed “more innovation, more participants in the market, more people trying to do some of the things we’re doing, because it creates noise and creates visibility”.
The lender distinguished itself with its interest-only product for first-time buyers last year, and, in defiance of initial scepticism and debate, McClelland found that other lenders now offered similar products.
Gen H has made it easier for its peers to innovate “rather than talk about it”, with McClelland saying: “When your only lever is price, you are going to lose because you don’t have the same pockets as big lenders. Obviously, we’re not the first to do something different in the mortgage market, but we’ve shown that it’s possible to grow from scratch, become sizeable and have an influence.
“I’m aware of other organisations that use us as an example when they’re in the boardroom”.
Generally, the lender’s customers fall under two categories: firstly, people who have gone through a life event like a divorce, death or illness and no longer fit the mortgage criteria they used to.
Secondly, by “democratising the availability of interest-only”, Gen H has also become a choice for people wanting to buy their second or third home.
Normalising interest-only
Earlier this year, the Financial Conduct Authority (FCA) showed its endorsement for interest-only mortgages with suggestions to redesign the way it worked, despite the product seemingly being in its last days.
McClelland said the regulator’s consultation implied the product was a “useful stepping stone” into homeownership, and although the FCA had never warded lenders away from the product, provision of interest-only diminished after the financial crisis as approaches to affordability changed.
The irony, McClelland noted, was that borrowers had been taking pseudo forms of interest-only mortgages since.
“Everyone used to take 25-year term mortgages, but now they’re taking 40-year terms. A 40-year term on a two-year fix looks a lot like an interest-only mortgage, particularly when many borrowers remortgage and continue with the longer term, rather than shrink it down,” McClelland added.
Any message from the regulator normalising interest-only helped, he said.
This could also break down “arbitrary barriers” to later life lending, which McClelland simply saw as lending.
“A lot of lenders change how they look at affordability as you get to certain ages. So, if you are going to bring interest-only mortgages back, it’s really important to look at this holistically. We are big believers that it’s good to get to retirement and have paid your mortgage off, but being retired with a small interest-only mortgage or similar is better than renting,” he added.
Gen H is a “big fan” of seeing the regulator tackle both lending propositions to improve provision for people who need or want to have a mortgage for longer.
Keeping things simple
McClelland believes offering straightforward mortgages without the complexities seen in propositions like Help to Buy or shared ownership is best, which is why its New Build Boost has a single loan, lender and point of valuation.
Then innovation can come from “being smart around affordability and complexity, which is where we focus our time”, and solving dilemmas such as people buying as part of a group or being unable to get a mortgage despite payments being lower than their current rent.
“Helping people with complex needs is probably the thing the industry can do better on,” he added.
For example, McClelland said self-employed borrowers and people with different income profiles benefitted from interest-only mortgages and taking this away had restricted some people’s access to finance.
On the right path
Referencing recent leadership changes, McClelland said the lender had been “pretty lucky” to have not gone through many changes with its management team, giving it continuity.
While he said it was a shame to see “good people leave the business”, he remained excited about its future.
“Six years ago, we hadn’t lent a pound to anybody. Fast forward to today, and we’ve lent around £2bn for customers,” McClelland said, adding that it had moved from the establishment phase to iterating and developing its proposition.
The recent executive changes will give its employees room to grow, which is why the lender was intentional about promoting from within.
“We feel we have an absolute tonne of exceptional people in the business,” McClelland said. Gen H has a “clear plan” for its future, which has instilled a “renewed vigour and energy” into its team, he added.